Seller's Guide • July 27, 2026

Think Nobody’s Buying Homes Right Now? Think Again.

If you’ve been thinking about selling, you’ve probably seen plenty of headlines suggesting buyers have just about disappeared. But there’s a big difference between a slow market and a stalled one.

Yes, mortgage rates are still higher than most people would like. Homes aren’t selling as fast as they were. And every week seems to bring another headline about buyers sitting on the sidelines. But here’s what you haven’t heard.


Despite everything going on, buyer demand has been remarkably resilient.

In fact, more sellers are getting to put up the “pending sale” sign now than during the last two years. What’s even more surprising is that they’re doing it at a time of year when activity usually starts to slow down.

And if you’re thinking about selling, that’s a trend worth paying attention to.


Buyers Are More Active Than You Think

One of the best ways to measure buyer demand is by looking at pending home sales. Those are homes that have gone under contract but haven’t closed yet. Think of them as a real-time pulse check on the market and whether buyers are still buying.

HousingWire Data shows more homes are going under contract than at the same time the past 2 years (see graph below):
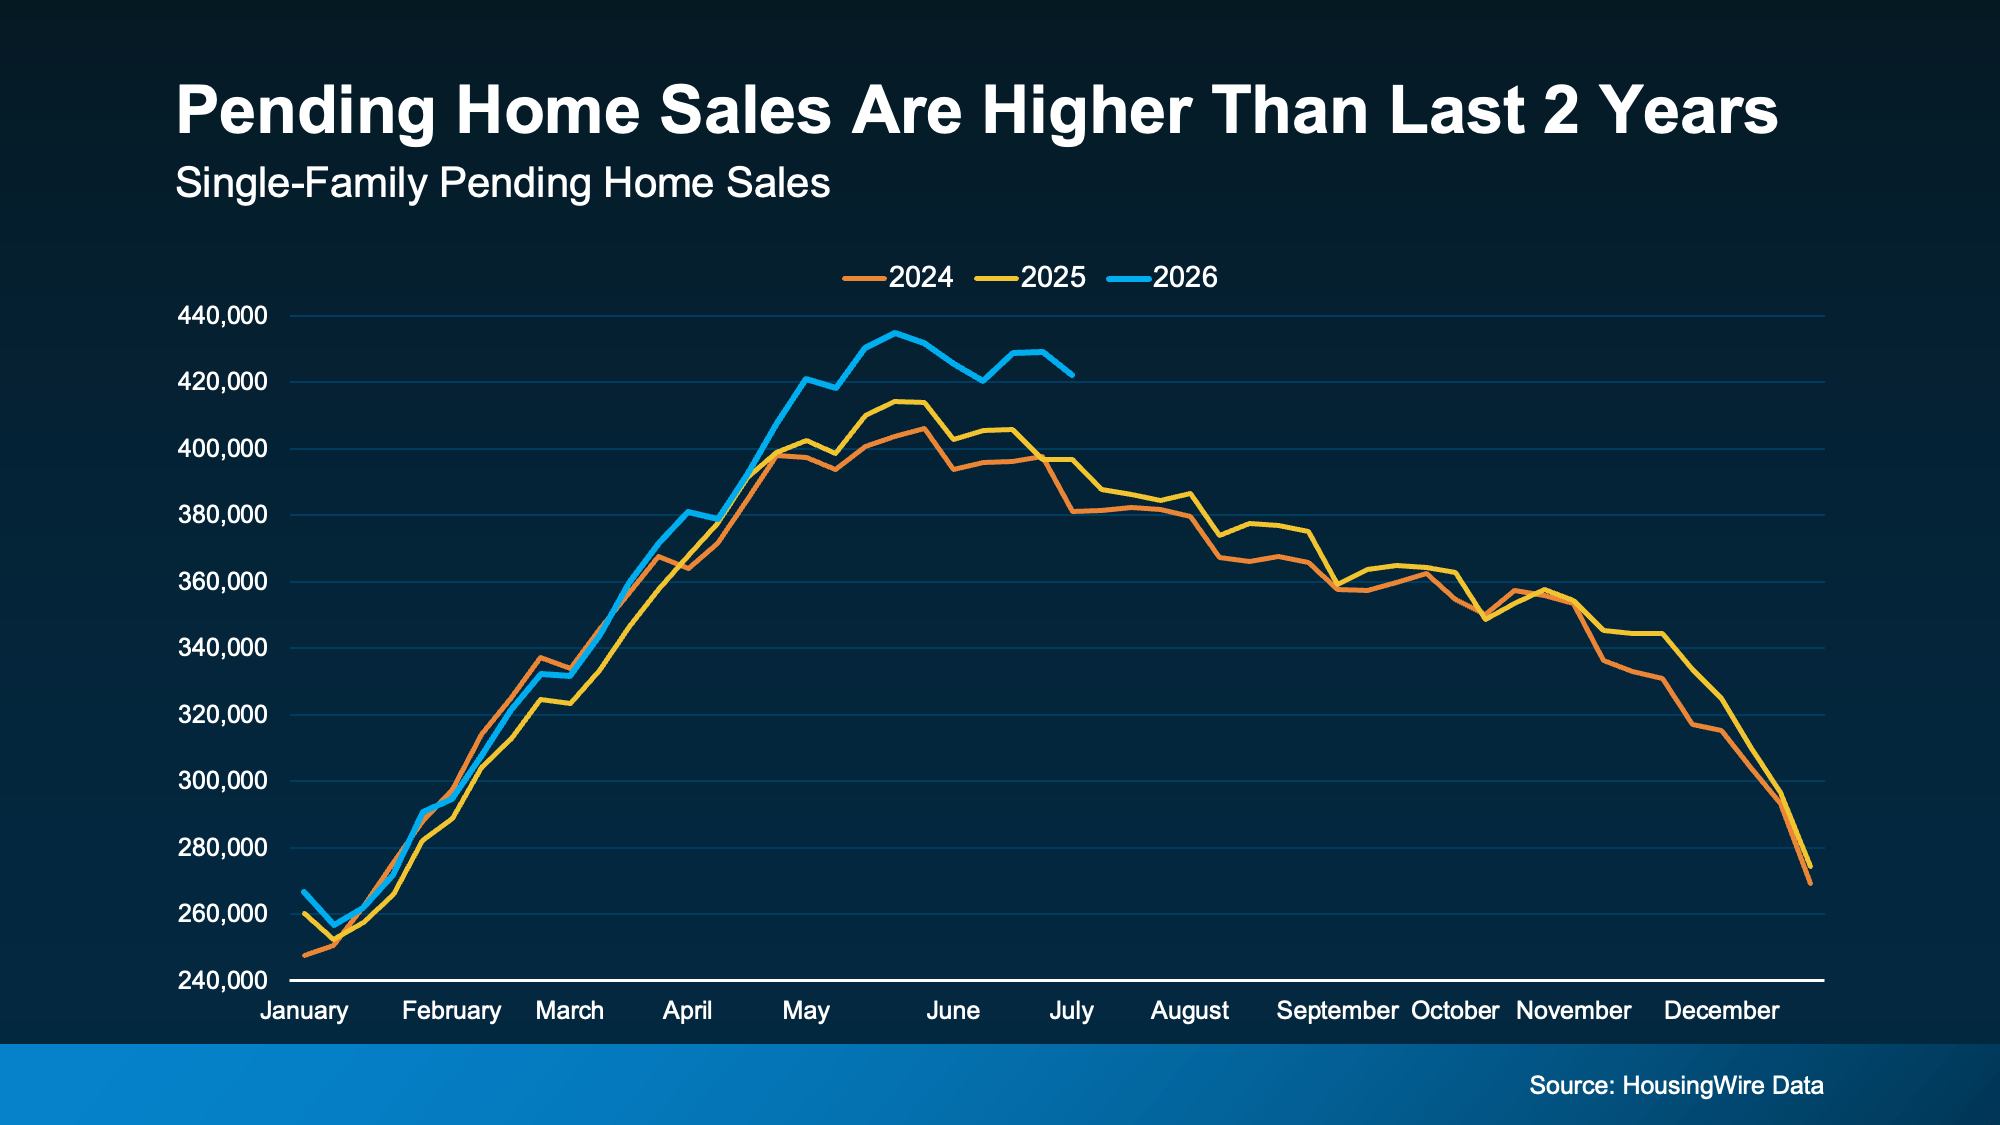
a graph showing the sales of a home sales

While it may come as a surprise, the numbers speak for themselves. It doesn’t mean buyers are everywhere, but it does mean they’re still active right now. And even if this ebbs and flows a bit in the weeks ahead, right now we’re still ahead of where we’ve been lately. That’s encouraging news if you’re thinking about selling because it tells us something important…


People haven’t stopped buying homes. Serious buyers are still making moves.

And a lot of these people are buying because they decided they can’t keep waiting. Whether it’s a growing family, a new job, retirement, or simply wanting a different home, life keeps moving… even when mortgage rates stay higher than we’d like. As Lawrence Yun, Chief Economist at the National Association of Realtors (NAR), explains:

“A late spring buyer rush—even with mortgage rates not budging—is an indication of pent-up housing demand and consumers’ acceptance of above-6% mortgage rates as the new normal.”

So, if you’ve been worried no one’s buying, this data should give you some confidence. Today’s buyers aren’t just casually browsing open houses on a Sunday afternoon, they’ve spent months waiting for rates to improve and now they realize they can’t wait anymore.

That means they have a purpose and a timeline. And that’s exactly the kind of motivated buyer you want to work with.


What This Means for Your Sale

Does that mean every house will sell instantly? No.

Today’s market is more balanced than it was a few years ago.  So, you can’t just price your house however you want or skip preparing it for the market.

Now buyers have choices, and they’re willing to wait for the right home at the right price. But sellers who understand today’s market (and price and position their homes right) are still finding success. Because the idea that “no one’s buying right now” just isn’t supported by the data.

The buyers are there.

The opportunity is there.

The key is having the right strategy to capture it.

Bottom Line

This year’s housing market may be moving slower than many of us hoped. But, buyer demand is more resilient than the headlines suggest.

If you’re wondering whether there are enough buyers for your house, let’s connect. I’ll show you what’s happening in our local market and build a strategy that helps you take advantage of the momentum that’s already here.

Buyer's Guide • July 17, 2026

The “Take It or Leave It” Attitude Is Fading from the Market – What That Means for You

Negotiations are back. More buyers are asking for better deals, and more sellers are giving them. Builders are throwing in extras, too.

That’s why whether you’re buying or selling today, there are two terms you’ll hear a lot: concession and incentive.

  • A concession is something a seller agrees to during negotiations to get a deal done.
  • An incentive is a perk a builder (or a seller) advertises upfront to attract buyers.

Let’s run through what you need to know about both and how they could play a role in your move.

More Sellers Are Agreeing to Concessions

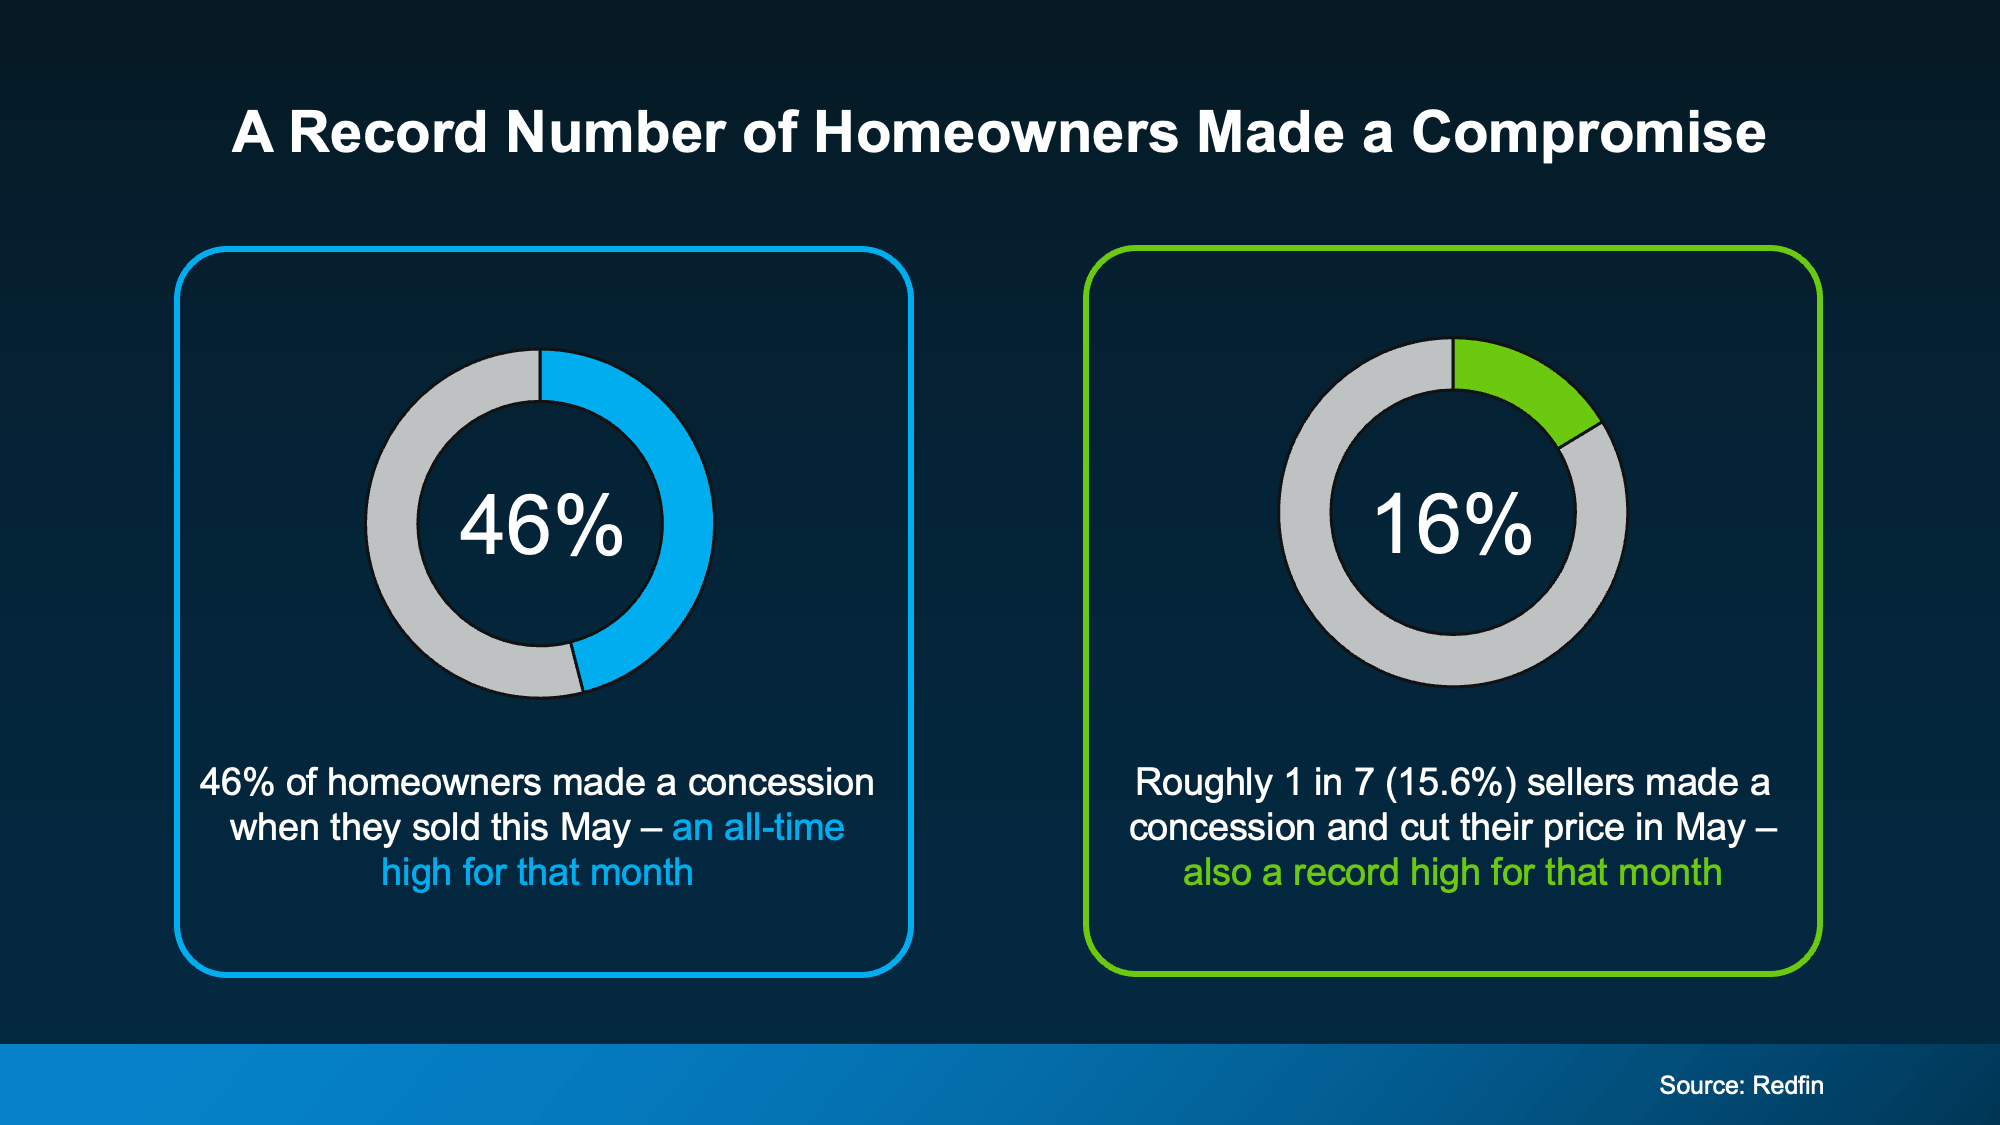
Almost half (46%) of homeowners who sold recently gave the buyer a concession, according to Redfin. That’s the highest share on record for this time of year. And roughly 1 in 7 (16%) sellers went a step further, cutting their asking price and offering a concession on top (see chart below):

a diagram of a homeowner's market

So, what kind of concessions are we talking about?

A seller might cover part of your closing costs, take care of a repair, or offer a credit that trims your upfront costs. It’s how they keep a deal on track when buyers have more options to choose from – and homeowners aren’t the only ones compromising.

Builders Are Cutting Prices, Too

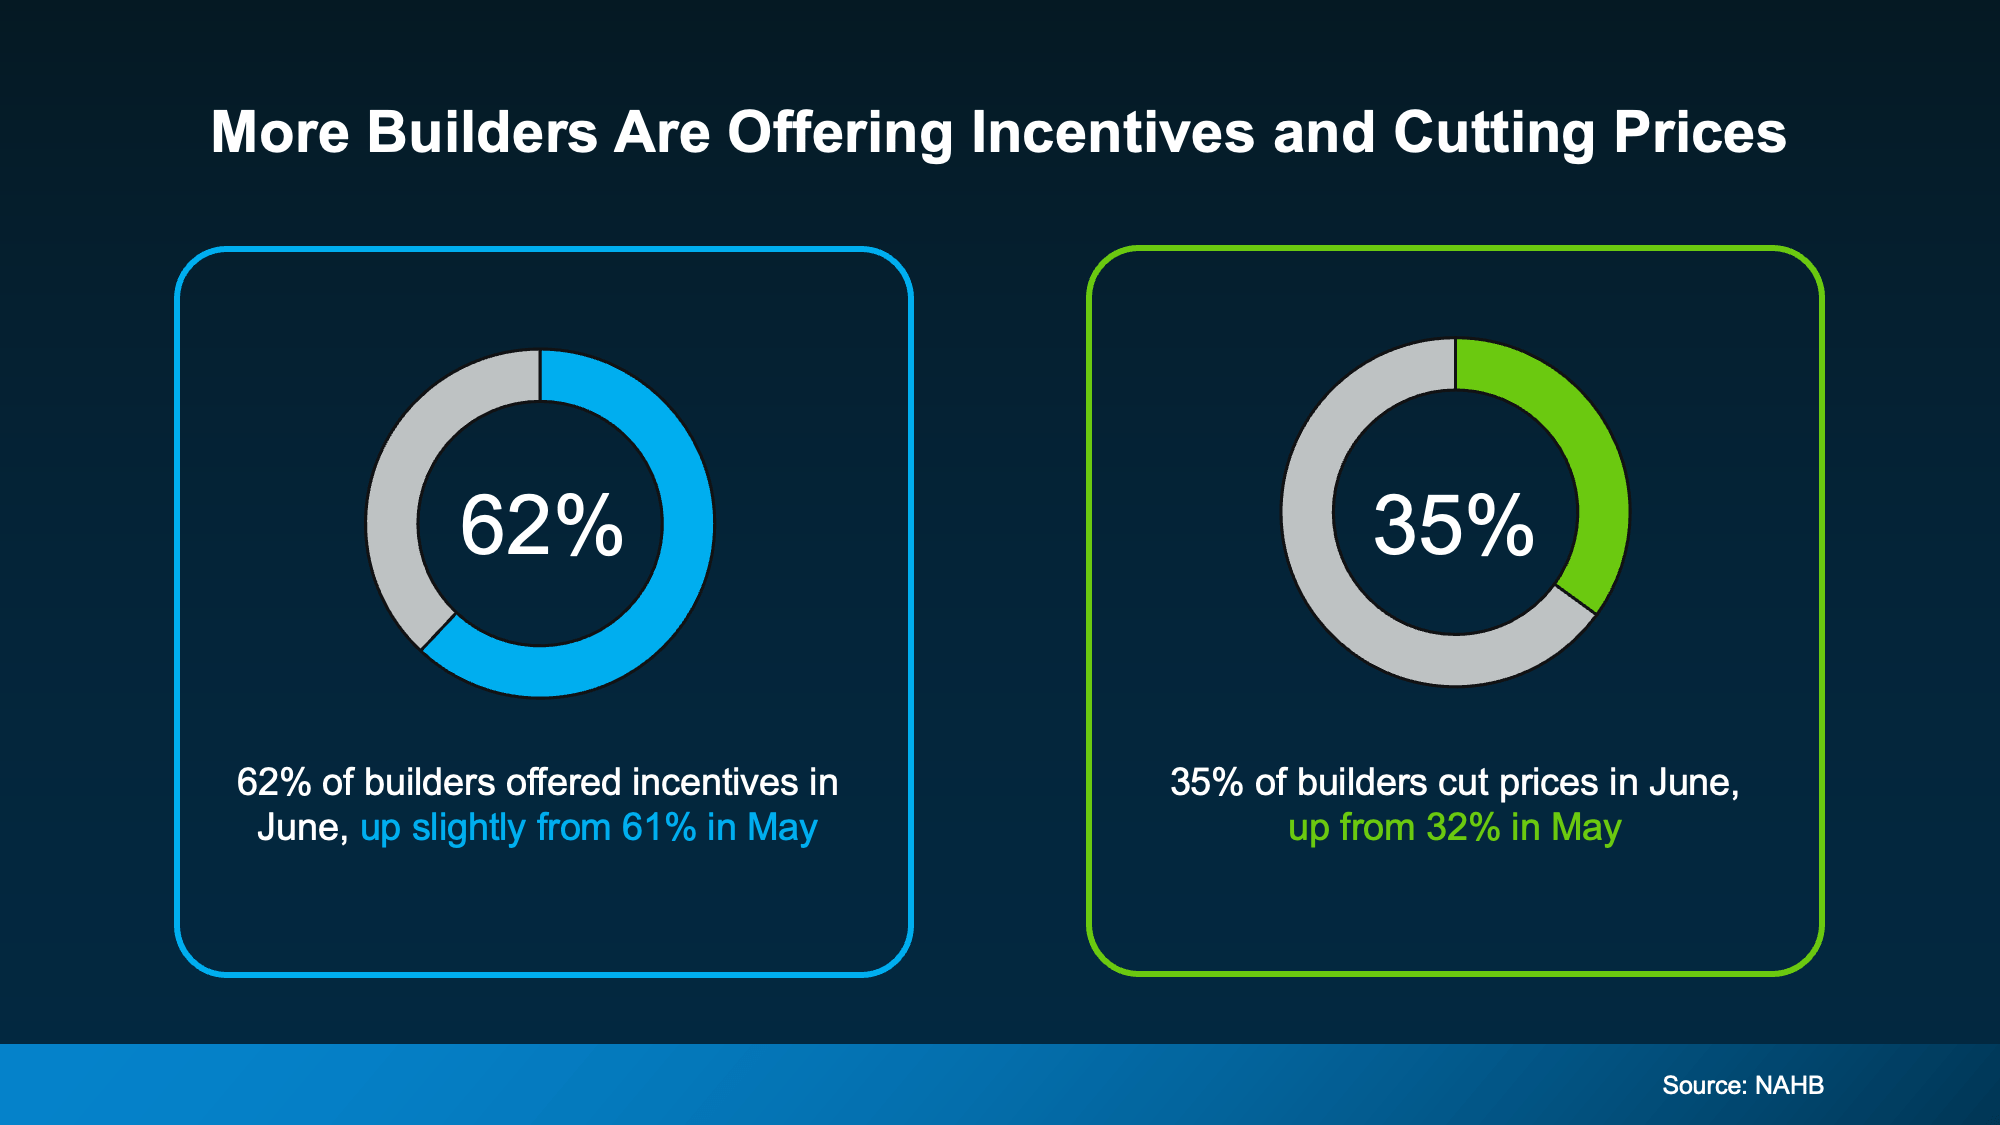
Newly built homes are seeing the same push and pull. According to the National Association of Home Builders (NAHB), 62% of builders are offering incentives right now. And about 35% are cutting prices outright (see chart below):

a screenshot of a graph

Those incentives often look like:

  • Price adjustments
  • Mortgage rate buydowns
  • Free upgrades, like nicer finishes or appliances

Danielle Hale, Chief Economist at Realtor.com, explains why:

“New construction has been one of the steadiest parts of the housing market over the past few years, but builders are clearly responding to today’s affordability pressures and higher levels of existing-home inventory.”

Even builders, who many people think rarely negotiate, are competing on price and perks. They have been for over a year now. The same data shows this is the 15th straight month where more than 60% of builders have offered incentives to sweeten the deal. And that’s significant.

What This Means for Your Move

If you’re buying, this is a good time to ask. Whether you have your eye on an existing house or a newly built home, there’s a chance the seller or builder will meet you partway on price, terms, or both.

If you’re selling, expect buyers to ask. Even builders of brand-new homes are making concessions more often than not right now. Holding firm on every term could mean more time on the market, or a lost sale altogether.

Bottom Line

Sellers and builders are both giving buyers more to work with this year. Want to know what’s realistic to expect in concessions and incentives in our market? Let’s connect.

Buyer's Guide • July 10, 2026

Down Payments Are Smaller Than They’ve Been Since 2021

Saving for a down payment can feel like the hardest part of buying a home. And with affordability as tight as it’s been lately, it’s fair to wonder how anyone manages it right now. Here’s something you may not have seen coming.

Some people are getting their foot in the door with a smaller down payment.

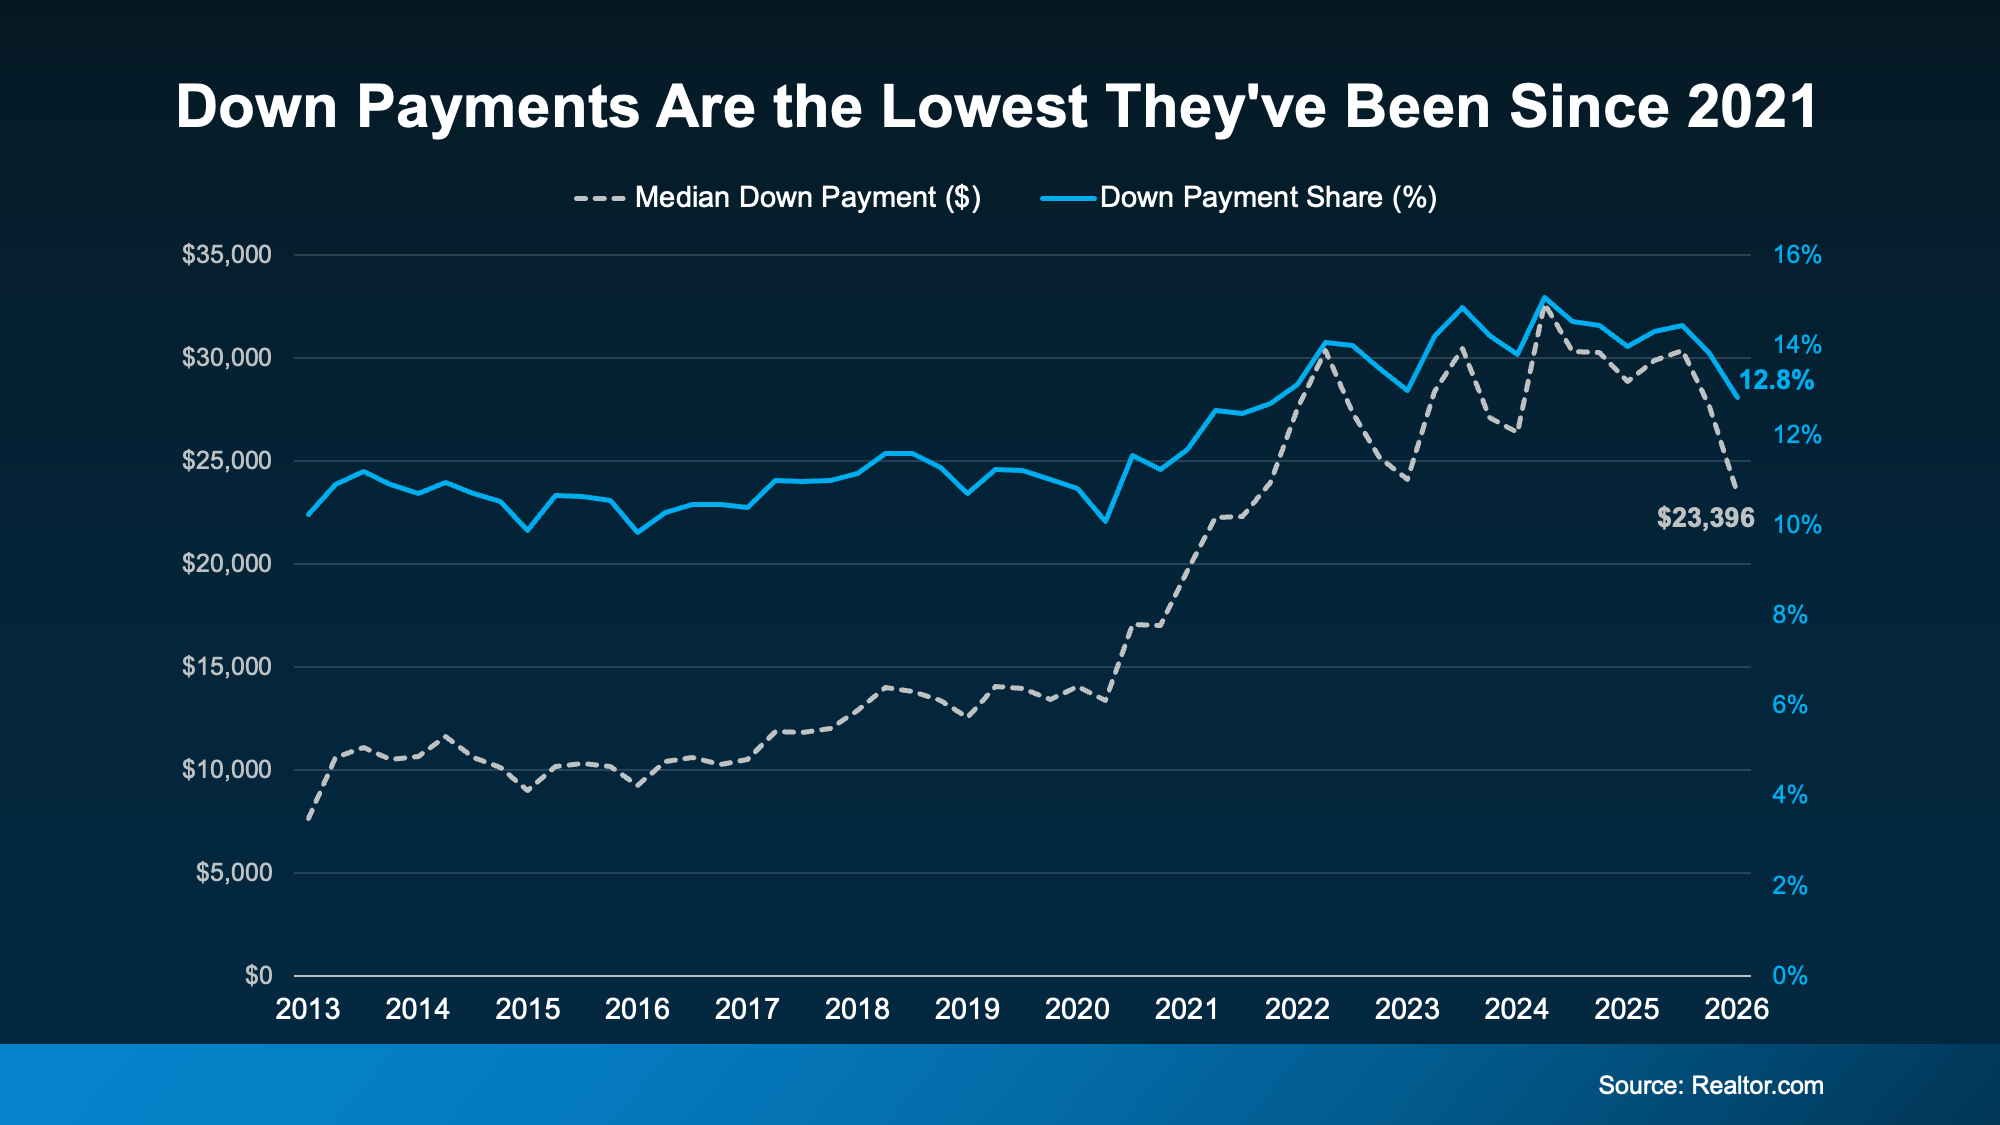
According to Realtor.com, the typical buyer put down about $23,400 in early 2026 – that’s around $5,000 below what was typical the year before (a 19% drop year over year). That’s the lowest down payments have been since 2021 (see graph below):

a graph of a line graph

So why are buyers putting less money down, and how can you put less down, too? Here’s your answer.


Why Down Payments Are Getting Smaller

There are a few things driving the trend:

  • Less competition between buyers. Part of it comes down to a more balanced market. With buyers facing less competition than they did a few years ago, there’s less pressure to put a big sum down just to stand out.
  • More moderate home prices. Your down payment is a percentage of the purchase price. So, as price growth cools, the amount you need to put down may change too. In a lot of markets, prices have slowed or leveled off, and some areas are even seeing slight dips. That can translate into smaller down payments.
  • Buyers opting for loans with lower down payments. More buyers are also turning to government-backed loans, like FHA and VA, which often need little or no money down. FHA loans have made up more than 24% of purchase mortgages for five straight quarters, and VA loans recently hit their highest share in over a decade, according to Mortgage Professional America.

But even a smaller down payment is still a significant chunk of cash, and saving it can be hard. So where does the rest come from? For many buyers, two things make the difference: programs built to help, and a hand from loved ones.


Help You May Not Know You Qualify For

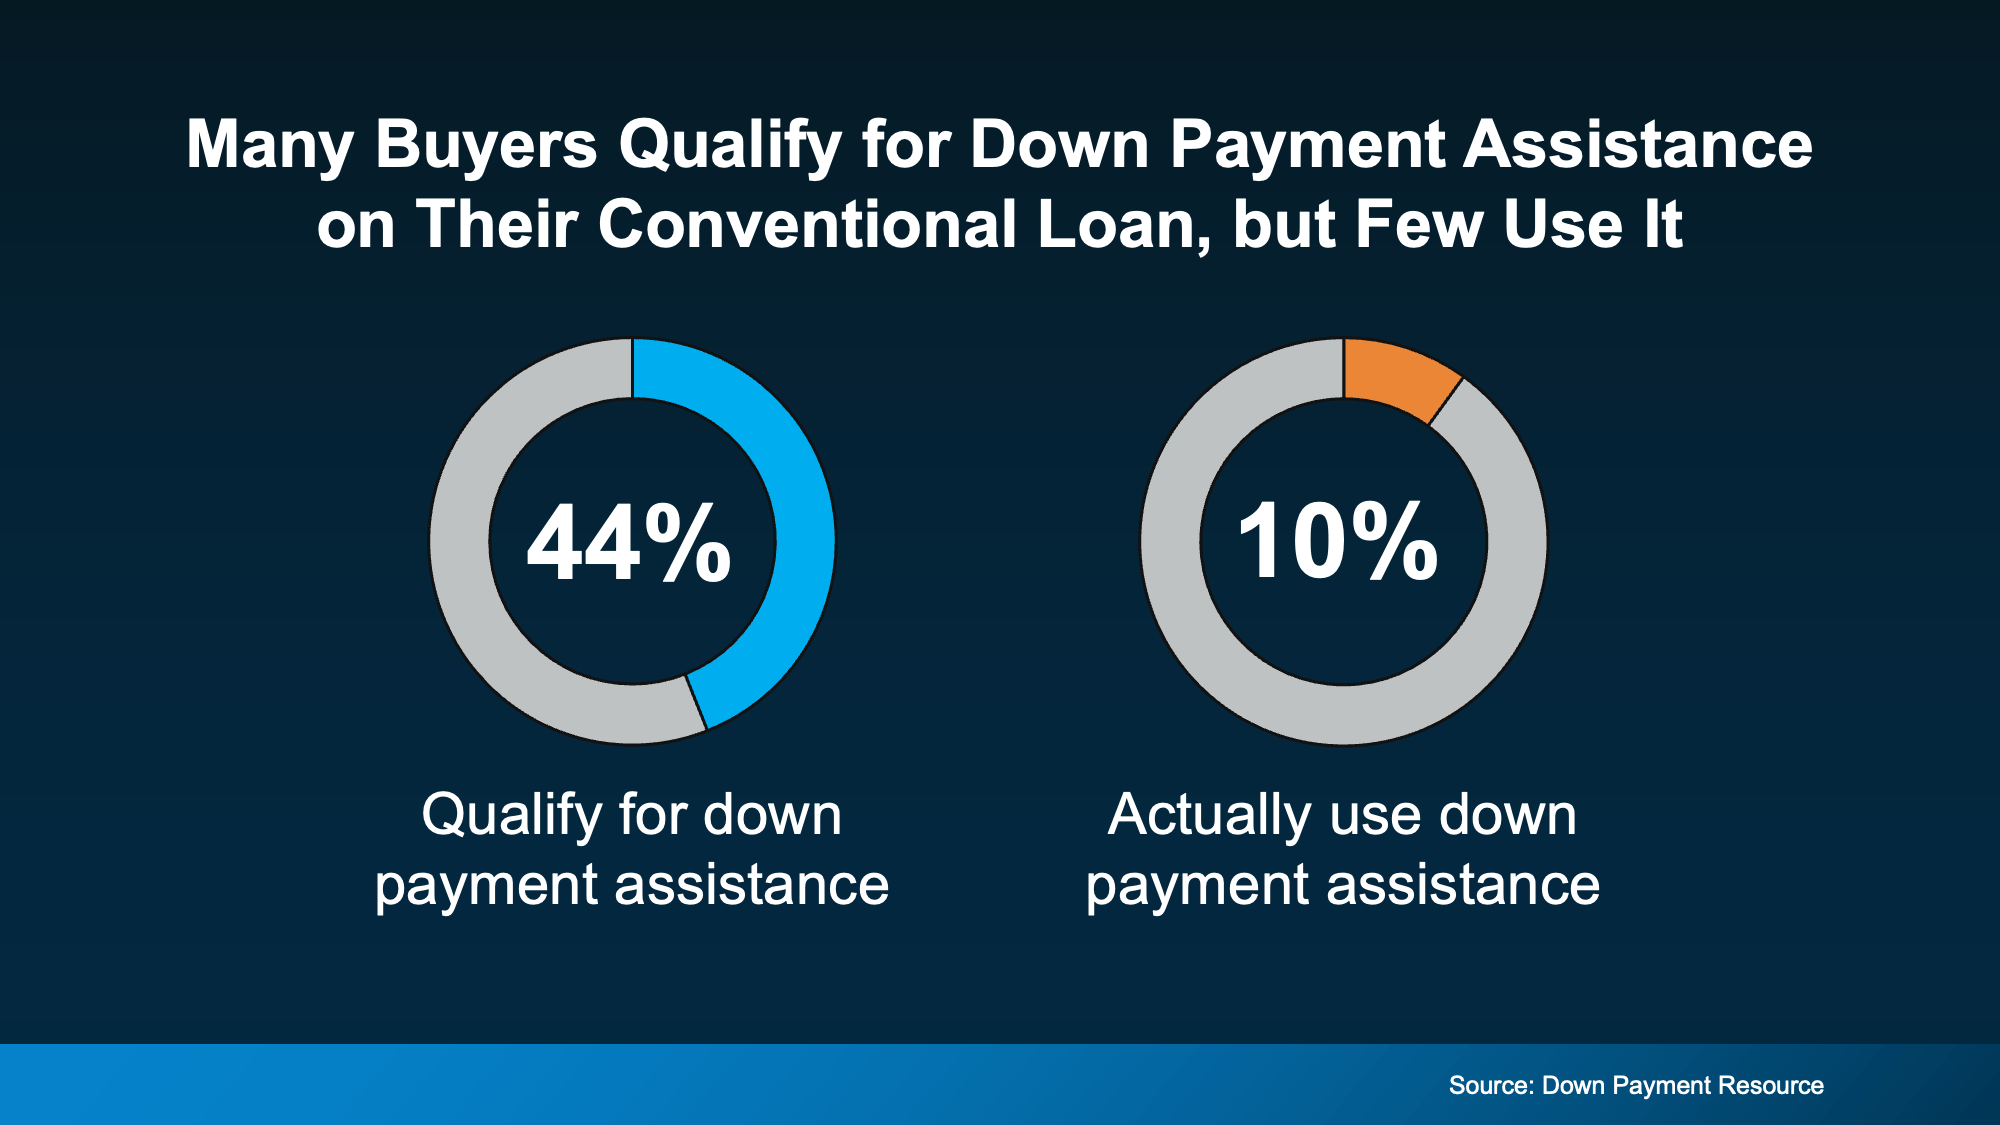
Down payment assistance is one of the most overlooked tools out there. Looking at the 10 largest U.S. metros, Urban Institute and Down Payment Resource found nearly 44% of recent buyers already qualified for a down payment program, but many of them closed on their loan without tapping the help (see chart below):

a diagram of a payment

The options are broader than you might assume, too. According to Down Payment Resource:

  • There are more than 2,600 down payment assistance programs available
  • More than half (62%) are designed to help first-time buyers
  • 38% have no first-time buyer requirement, so you may qualify even if you’ve owned before
  • 62% are open to buyers earning $100,000 or more


A Boost from Loved Ones

For a growing number of buyers, help comes from closer to home. Research from Veterans United shows about 59% of parents have provided or plan to provide financial support to help their child buy a home.

That support most often goes toward the down payment, followed by help qualifying for a mortgage and covering closing costs. Chris Birk, VP of Mortgage Insight at Veterans United, puts it this way:

“For many families, helping a child buy a home has become less of an optional gesture and more of a practical response to today’s affordability challenges.”

If your loved ones are in a position to help, it can make a real difference in how soon you can buy.

Bottom Line

Down payments are smaller than they’ve been in years, and that opens the door for more buyers.

And with added help from assistance programs and a little help from loved ones, you may have more ways forward than you realized. Connect with a trusted lender to talk through your options.

Buyer's Guide • July 3, 2026

The 1 Factor That Explains Everything Happening with Home Prices Right Now

You’ve probably heard that home prices are cooling off. And that’s true – nationally. But zoom in on individual markets across the country, and the picture looks completely different depending on where you are.

Some areas are still seeing solid price growth. Others have gone flat. A few have actually dipped slightly negative. So, what’s causing all of that variation? 

It All Comes Down to Inventory

Here’s the simple version:

  1. When there are more homes for sale, buyers have options.
  2. More options, means less competition.
  3. Less competition means sellers can’t push prices as high.

On the flip side, when inventory is tight, buyers are competing over a small pool of homes, and that pushes prices up.

That dynamic is playing out right now in a really visible way across the country.

Markets where inventory has climbed back to, or above, normal pre-pandemic levels are seeing prices flatten or fall slightly. Markets where inventory is still well below those 2019 benchmarks are still seeing prices rise. As Lance Lambert, CEO of ResiClub, puts it:

“Home prices are still climbing a little year-over-year in many regions where active inventory remains well below pre-pandemic 2019 levels, such as pockets of the Northeast and Midwest.

In contrast, some pockets in states like Texas, Florida, and Colorado — where active inventory exceeds pre-pandemic 2019 levels by a solid clip — are seeing modest home price pullbacks or flat pricing.”


The Maps Say It All 

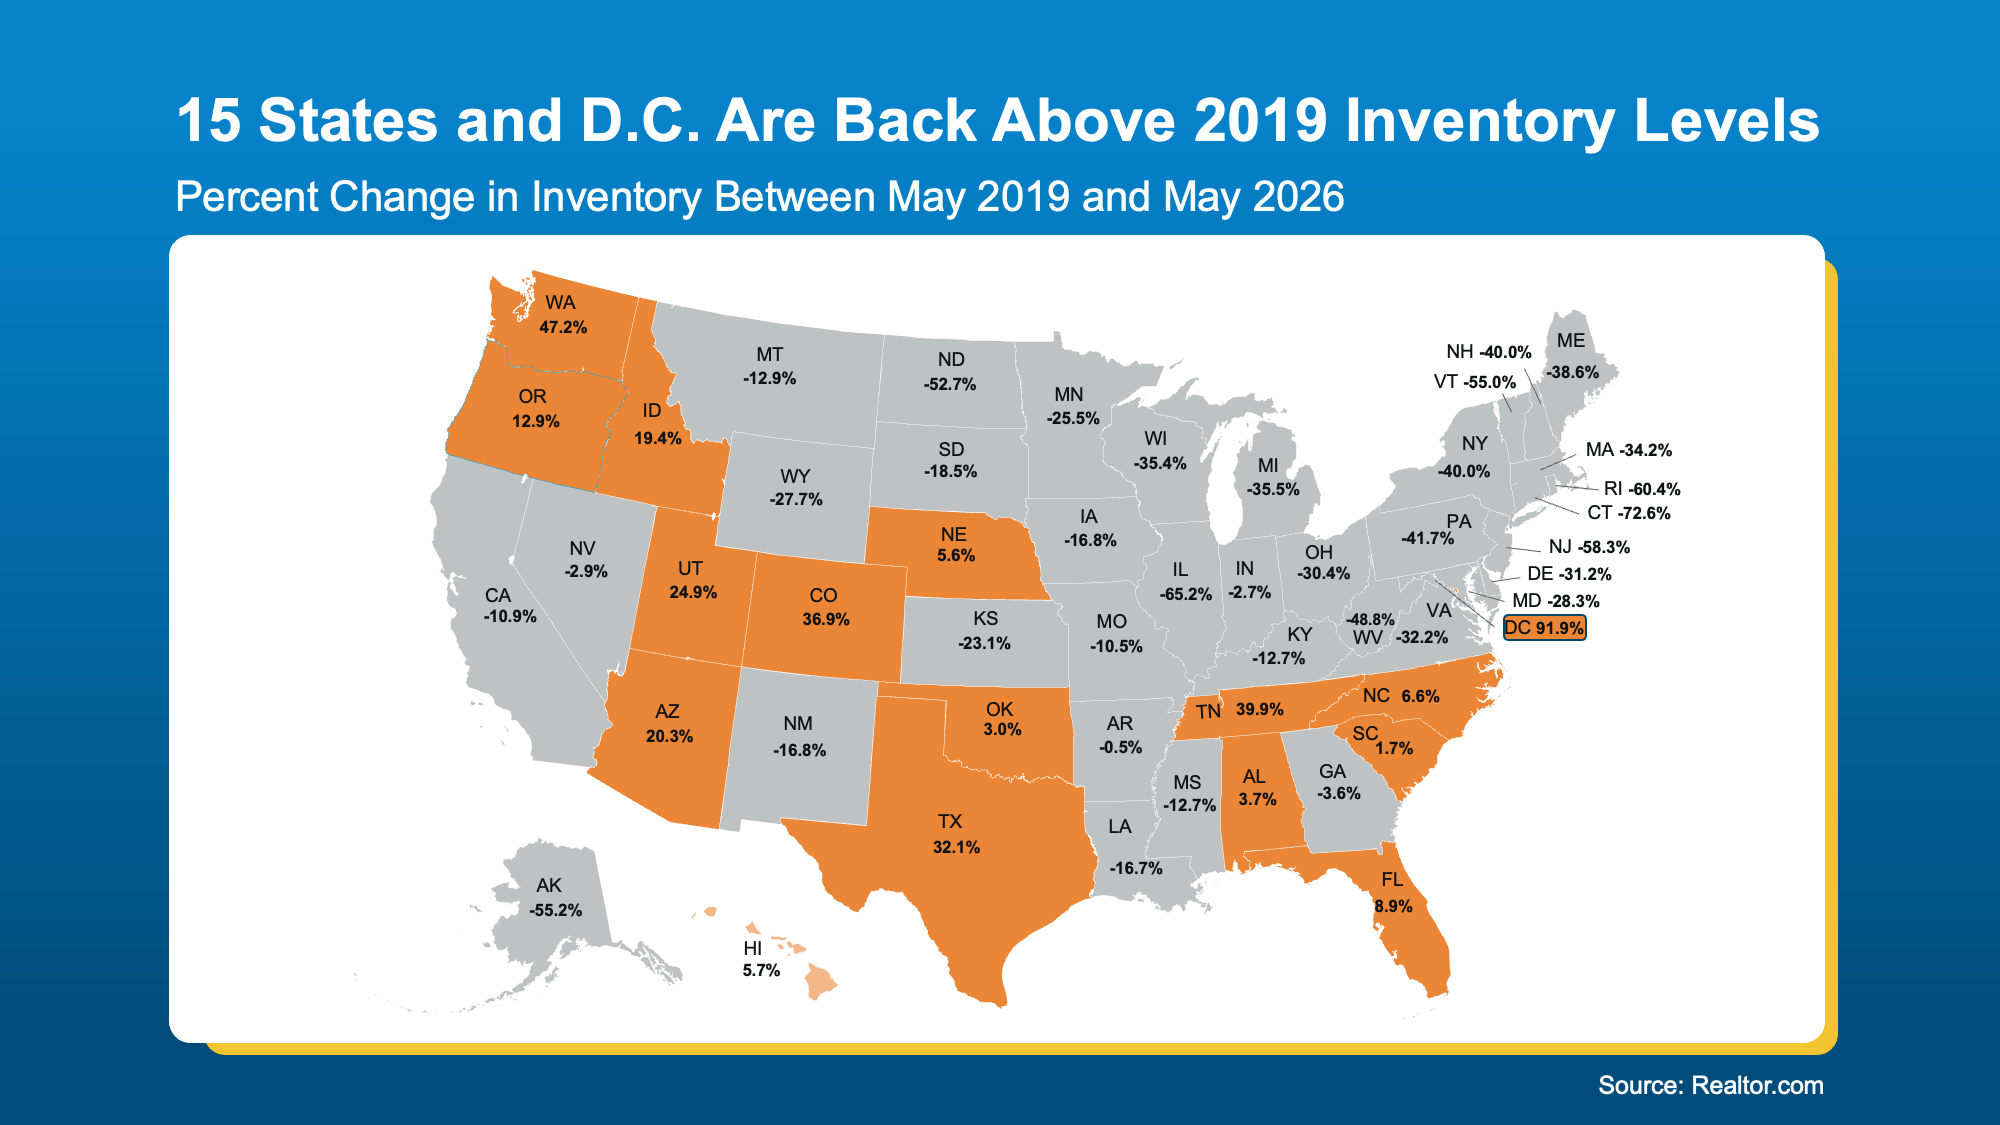
Take a look at where inventory stands today compared to 2019. In most places (the states in gray below), inventory still falls short of where we were back then. And that’s exactly why prices are climbing, albeit moderately, in the vast majority of states.

But you’re probably more interested in where prices are falling a bit, since that’s what is making headlines. So, let’s prove out how much inventory affects prices in those spots.

According to Realtor.com, 15 states and Washington, D.C. are now back above pre-pandemic inventory levels, and some by a wide margin (see the orange in the map below):

a map of the united states

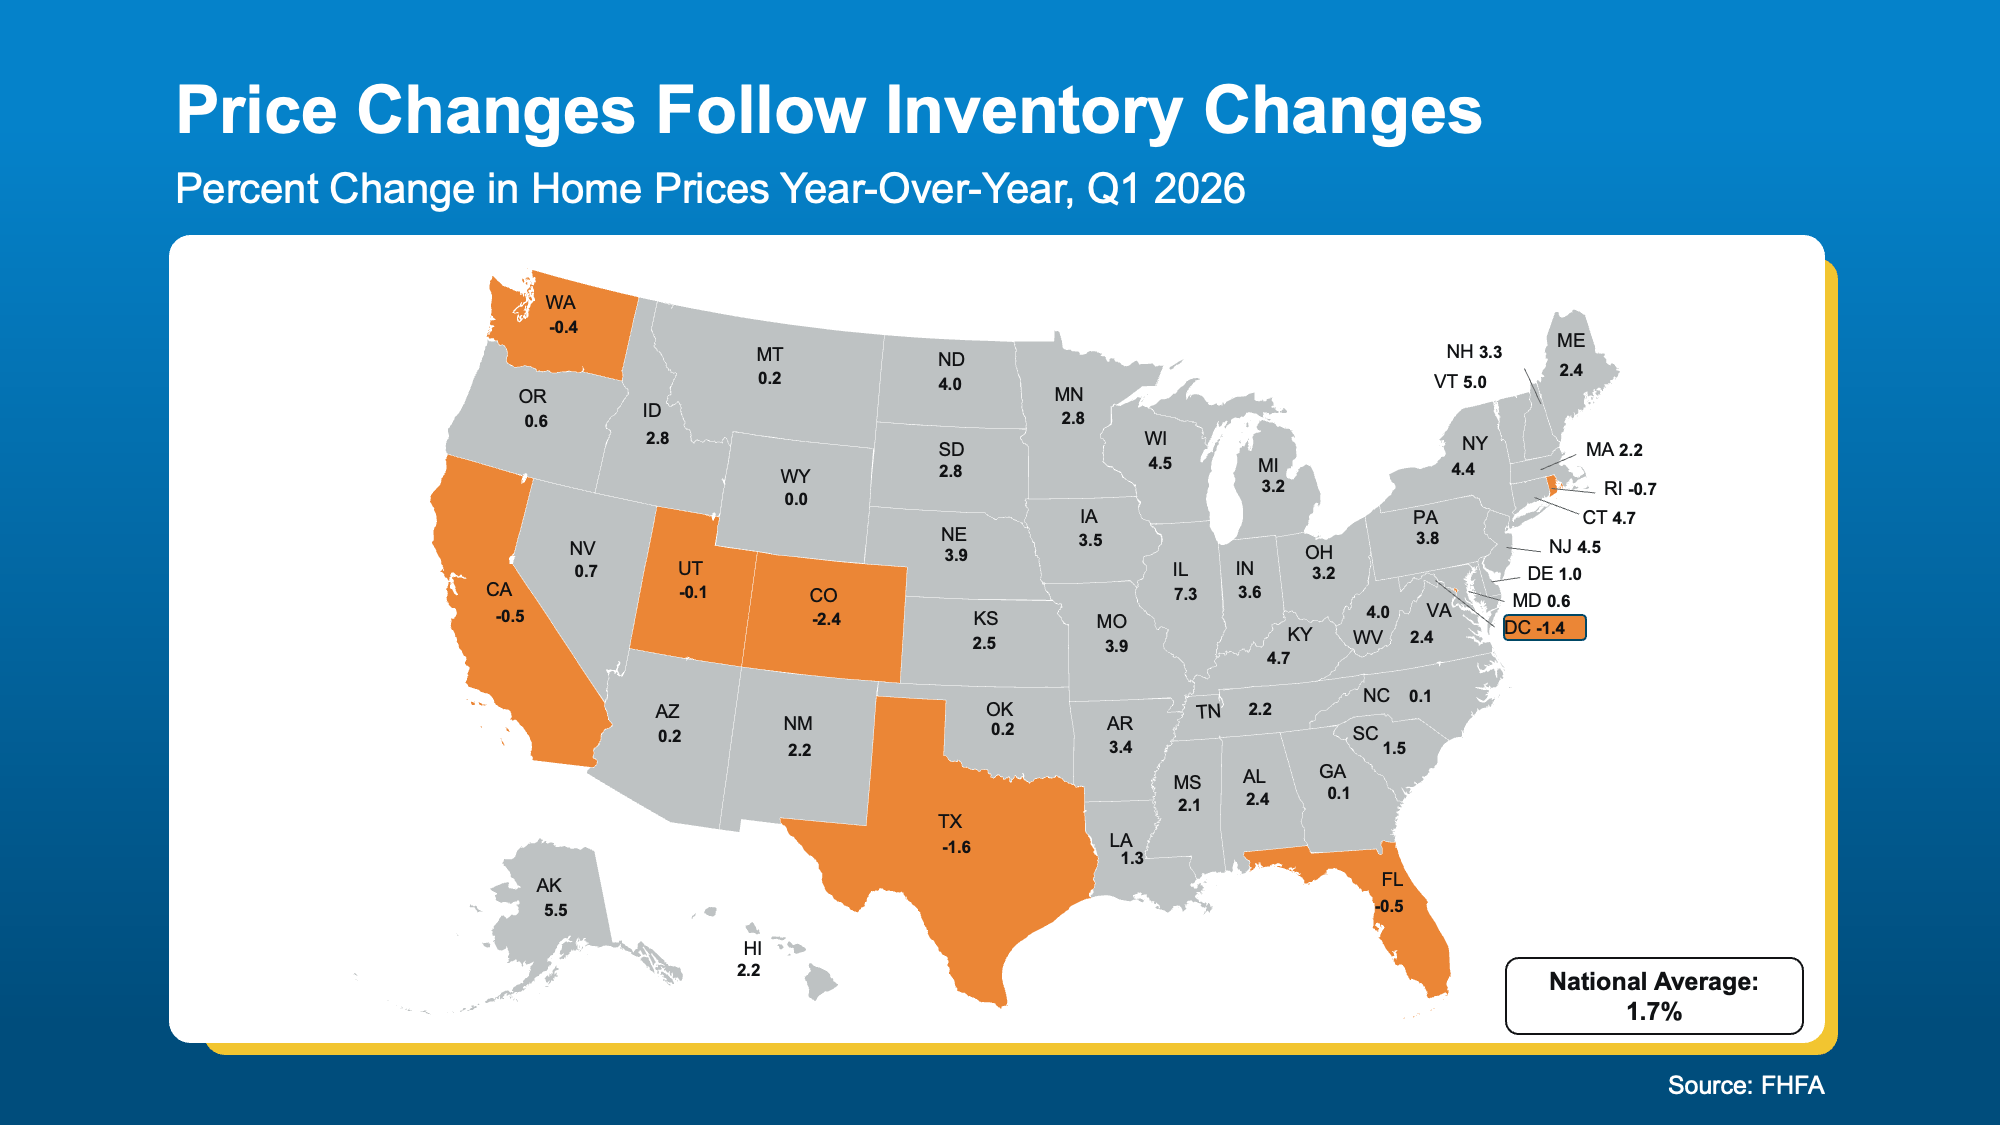
Now, let’s look at the latest Federal Housing Finance Agency (FHFA) data to see what’s happened to home prices in those same states over the past year (again, you’ll want to focus on the orange in the next map).

See how those line up pretty closely with the areas seeing more homes for sale today?


The overlap isn’t a coincidence. It’s cause and effect.

a map of the united states

The national average of 1.7% price growth is accurate, but it’s an average of two very different stories happening at the same time – the few areas experiencing mild declines and the overwhelming majority that are still seeing prices rise.


What This Means If You’re Buying or Selling 

If you’re a buyer, the market you’re shopping in matters a lot right now. In places like Texas, Colorado, or Florida, you may have real negotiating power – more choices, less competition, and sellers who are more motivated to make a deal. In tighter markets like much of the Northeast, you’re still likely facing a lot of competition.

If you’re a seller, pricing strategy is everything. In markets where inventory has risen, overpricing is one of the fastest ways to linger on the market and eventually sell for less than you would have with the right price from day one. In markets where inventory is still low, you’re in a strong spot, but getting your price right still matters if you want to attract serious buyers quickly. Either way, that’s where a local real estate agent earns their keep.

Bottom Line

When it comes to prices, where you are matters more than ever right now, and a local real estate agent is the best person to help you make sense of it.

Reach out today and let’s build a plan that fits our market.

Buyer's Guide • June 25, 2026

Is It Still a Seller’s Market? Here’s What the Data Says.

Remember a few years back when sellers held all the power and buyers were stuck offering way over asking or waiving inspections just to get a chance at the house? In many markets, those days are behind us.

While it’s going to vary by area, more metros are slowly shifting to favor buyers, and the market is starting to look a lot more like a two-way street again.


And that balance is something we haven’t had in a while.

Whether you’re buying or selling, here’s what you need to know about what’s changing and what it means for your move.


The Most Buyer-Friendly Market in Years

The national data tells an interesting story right now. According to Realtor.com:

“The national housing market is balanced but gradually loosening as the cycle moves in a more buyer-friendly direction . . .“

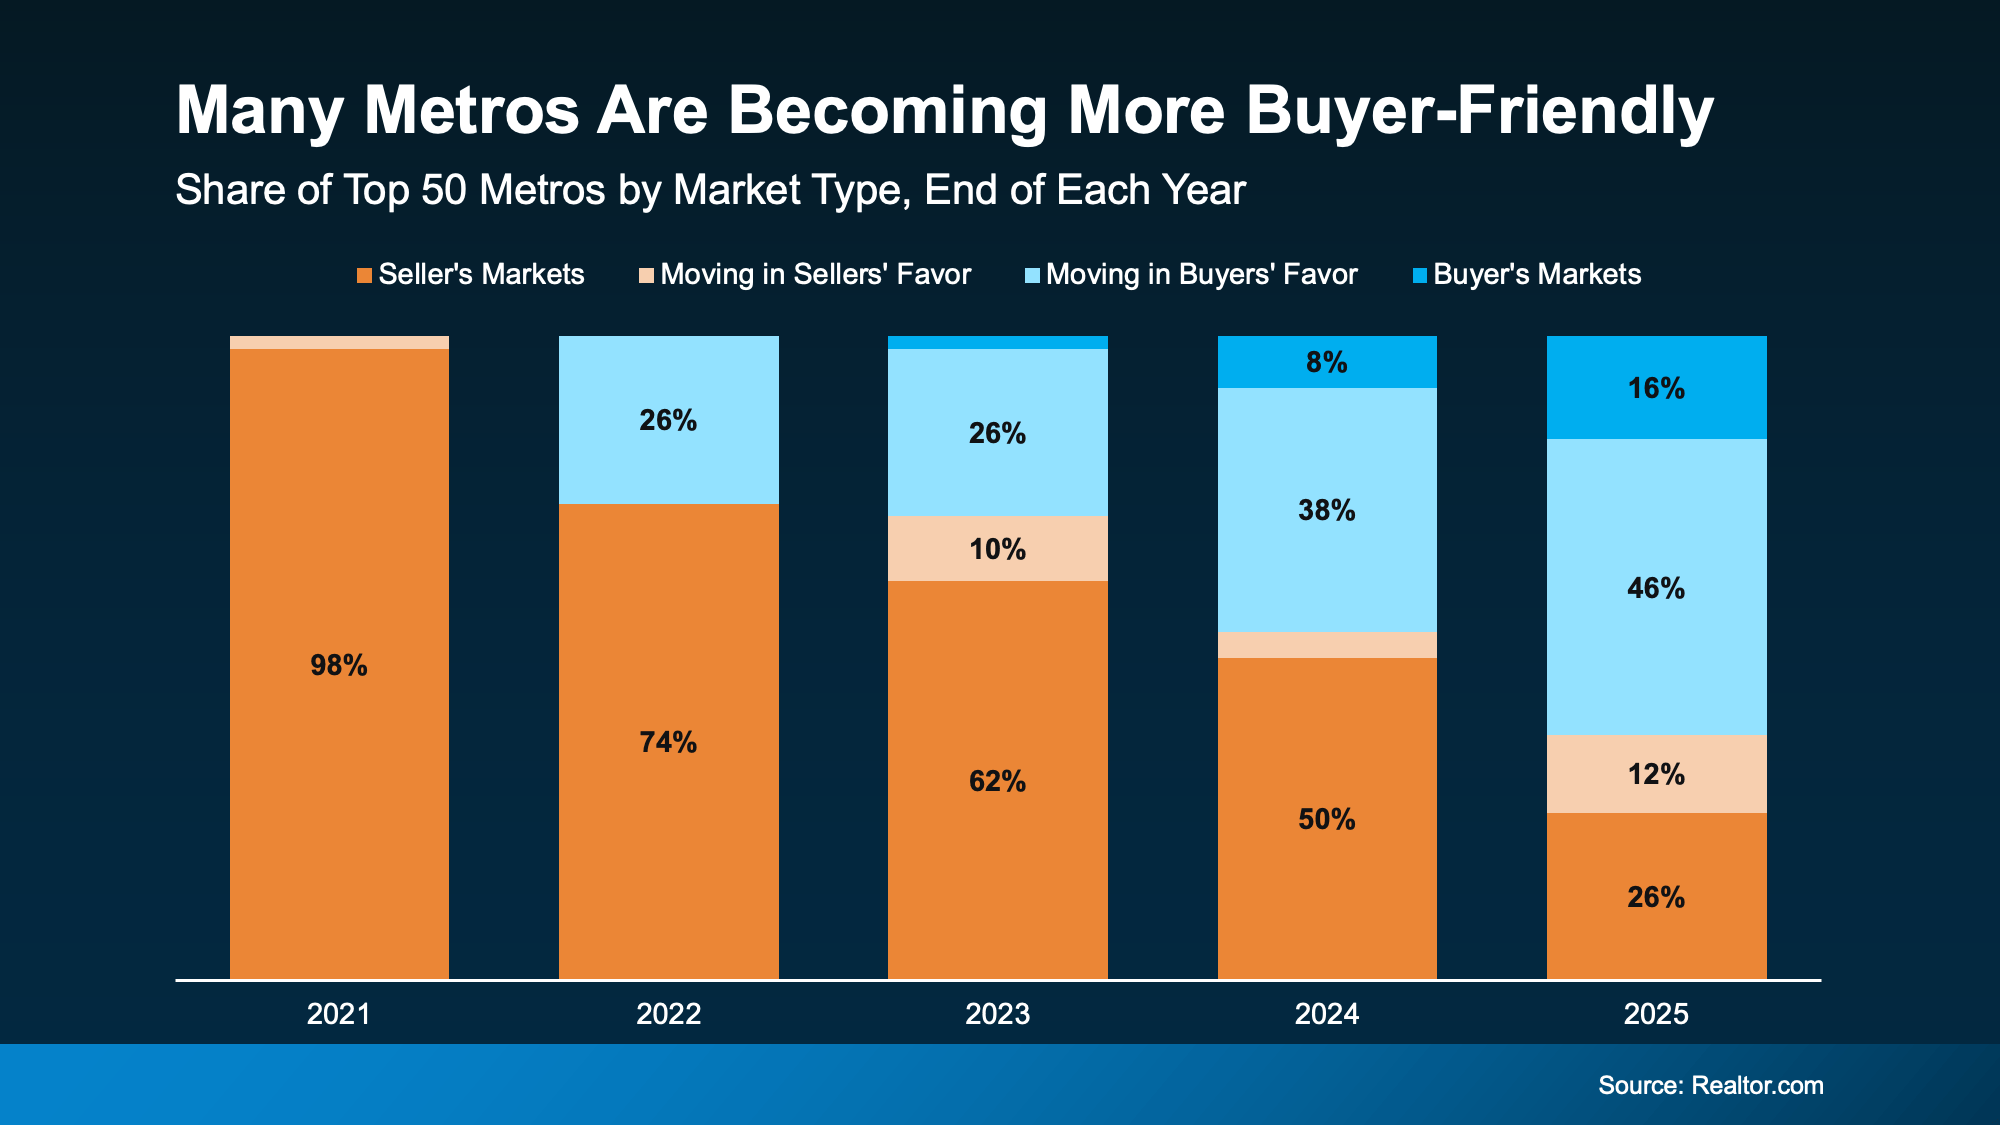
That’s because, over the past few years, more and more metros have been flipping back to more buyer-friendly terms as inventory’s grown. And when you zoom in on the latest Realtor.com data for the top 50 metro markets over time, the trend becomes really clear (see graph below).

Back in 2021, almost all major metros were seller’s markets. By the end of 2025, only 1 in 3 still favored sellers. That’s an obvious shift.

a graph of sales

And that changes how the market is going to feel for everyone. Sellers shouldn’t still expect 2021 conditions, but neither should buyers. At least, not generally speaking.


It’s Not the Same Story Everywhere

That said, who has the power ultimately depends on where you live. While more metros are leaning buyer-friendly lately, there are still plenty of strong seller’s markets right now, too.

It really comes down to how much housing supply and demand there is in your area. And that varies enormously by region.

Sun Belt cities like Austin, Tampa, and San Antonio saw major building booms in recent years, giving buyers more options and more negotiating room. Meanwhile, cities in the Northeast and Midwest – think Rochester, Hartford, and Buffalo – didn’t see that same wave, so inventory stayed tight and competition stayed fierce. As Jeff Ostrowski, Housing Analyst at Bankrate, explains:

“The formerly hot Sun Belt markets have cooled, while the Northeast and Midwest have stayed hot. The big driver here is construction activity. The softest markets now [have] experienced big booms that spurred new building, and that has led to a large supply of new and existing homes on the market in those places.”


Practical Advice for Your Move

To find out who has the power in your local market, talk to an agent. Because knowing what’s happening locally is going to be the key to setting the right strategy for your move.

If the market is working in your favor, great. Lean in and use it to your benefit. But if it’s not, all hope isn’t lost. Your agent can help you figure out how to approach any market.

Here’s some practical advice if there’s a mismatch between your goal and local market conditions.

If you’re buying in a seller’s market:

  • Get pre-approved before you start shopping. It shows sellers you’re serious.
  • Be ready to act fast when the right home hits the market.
  • Consider offering a quick closing date or flexible terms.
  • Work closely with your agent to craft a competitive offer.

If you’re selling in a buyer’s market:

  • Price it right from day one. Overpricing will cost you time and money.
  • Focus on curb appeal and staging to stand out in areas with more inventory.
  • Be open to offering incentives, like covering closing costs or a home warranty.
  • Expect buyers to negotiate and be ready to be flexible.

Bottom Line

Right now, local markets are moving in very different directions. And your strategy as a buyer or seller should reflect your market.

Want to know which way our local market is leaning and what that means for your move? Let’s connect.

Buyer's Guide • Seller's Guide • June 20, 2026

Should You Pay for Your Buyer’s Closing Costs? What Sellers Need To Know.

A few years ago, sellers could get away with saying “no” to just about everything.

  • No repairs.
  • No concessions.
  • No negotiation.

If buyers wanted the house, they pretty much had to take it on the seller’s terms. But now that inventory’s grown, negotiations are becoming a normal part of the process again.

That’s why one of the most important things sellers need to understand right now is this:


The goal isn’t to “win” every negotiation.

Sometimes, it’s worth meeting buyers where they are to get a deal done, fast. One example? Helping with a buyer’s closing costs.

Let’s break that down, so you know what to expect if it comes up in your sale.


What Are Buyer Closing Costs?

Closing costs are the extra expenses buyers pay on top of their down payment when they purchase a home. Freddie Mac gives some examples:

  • Loan origination fees
  • Appraisal and inspection costs
  • Title and attorney fees
  • Survey fees and more

Typically, buyer closing costs range from about 2% to 5% of the home’s purchase price. So, on the typical $400,000 home, that could mean anywhere from $8,000 to $20,000 out of pocket.

And in today’s affordability-challenged market, that upfront cash can be a major hurdle for some buyers – even if they can comfortably afford the monthly mortgage payment itself.

That’s why more people are asking sellers for help.


And More Sellers Are Saying “Yes”

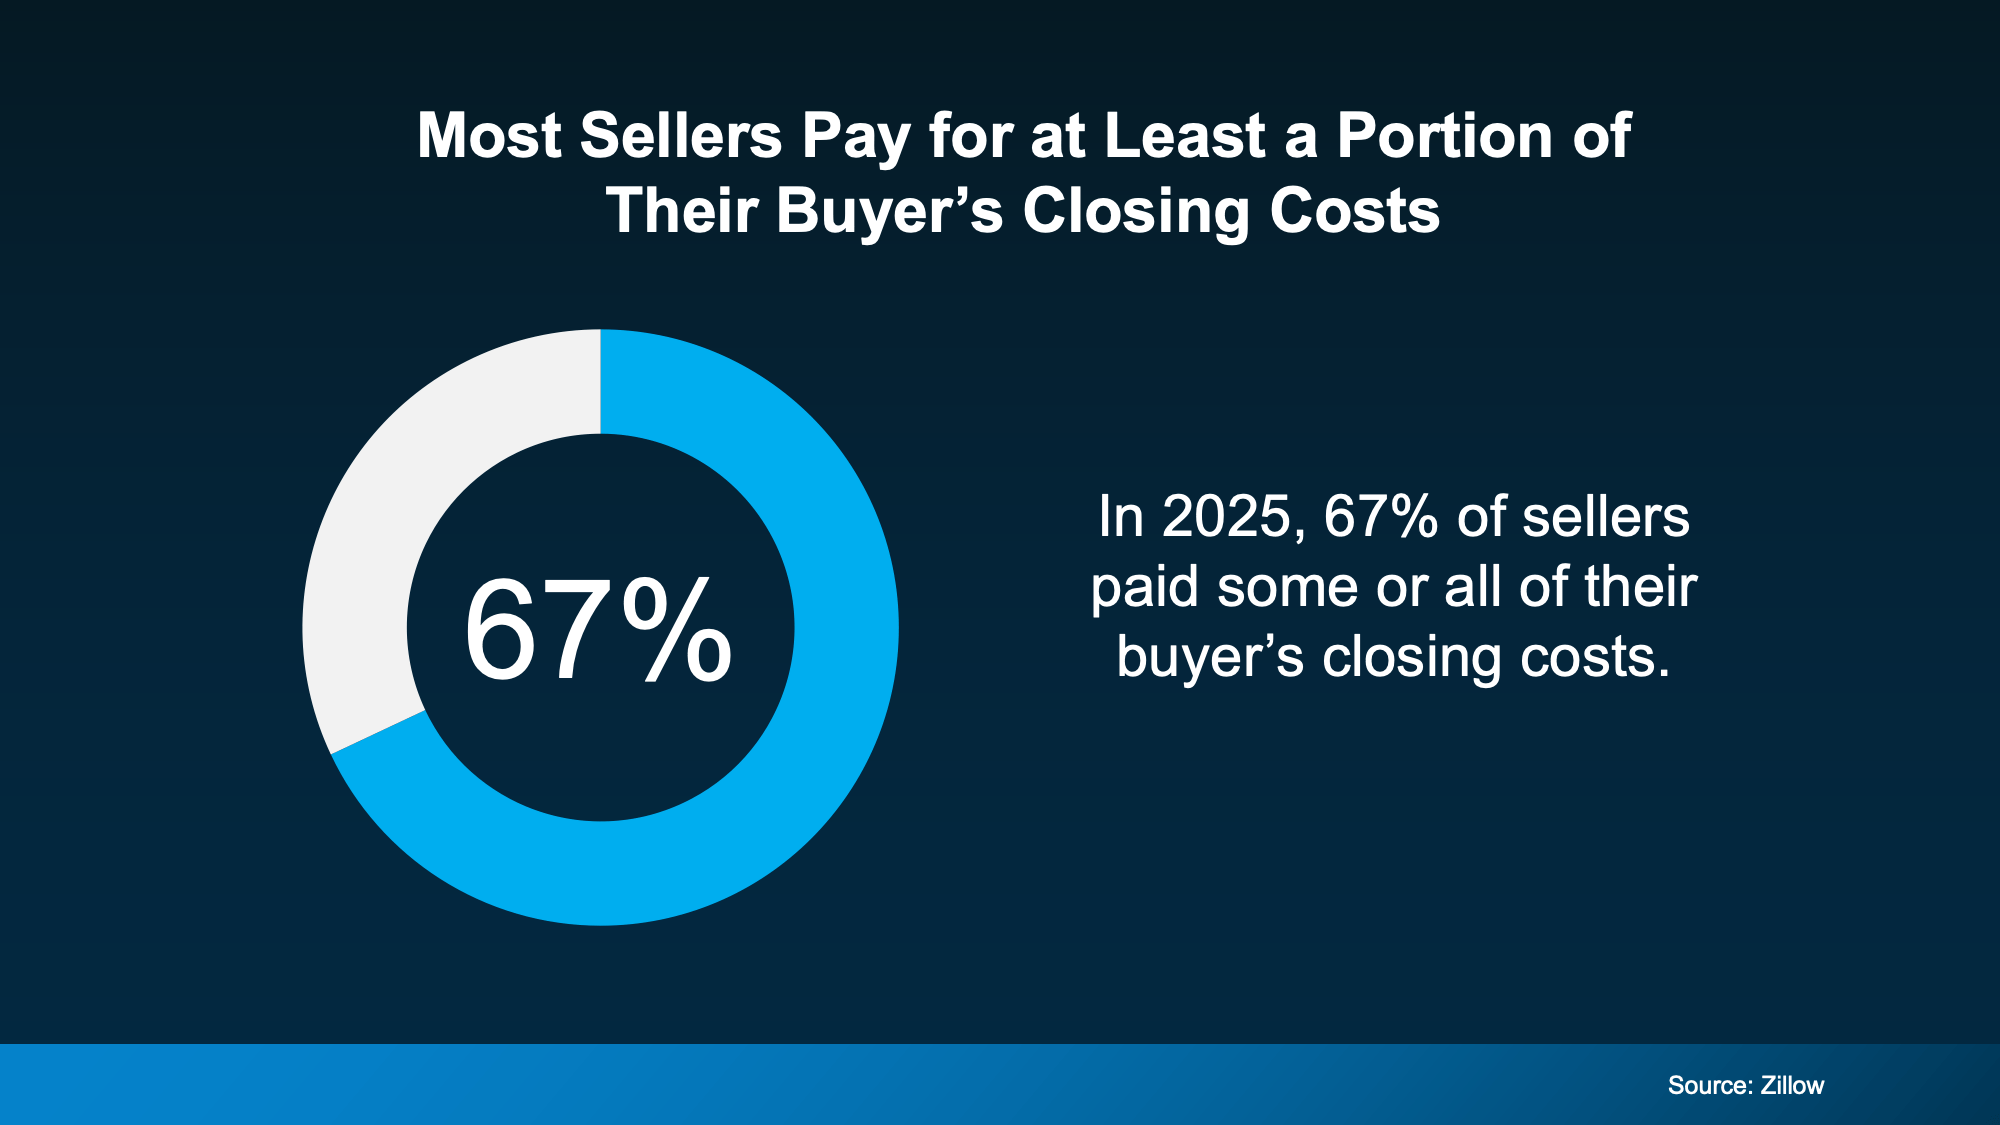
According to the latest data from Zillow, 67% of sellers reported paying some or all of the buyer’s closing costs in 2025 (see chart below):

a blue circle with white text

Now, that doesn’t mean every seller is doing it. And it definitely doesn’t mean every seller should. But it does show how common concessions have become as the market has shifted. And that’s important for you to know.


When Paying Closing Costs May Make Sense

This is where many sellers get stuck. They hear “help with closing costs” and immediately think: “Why should I pay for their expenses?”

But that’s not always the right way to look at it. You’ve got to consider who has the leverage in today’s market.

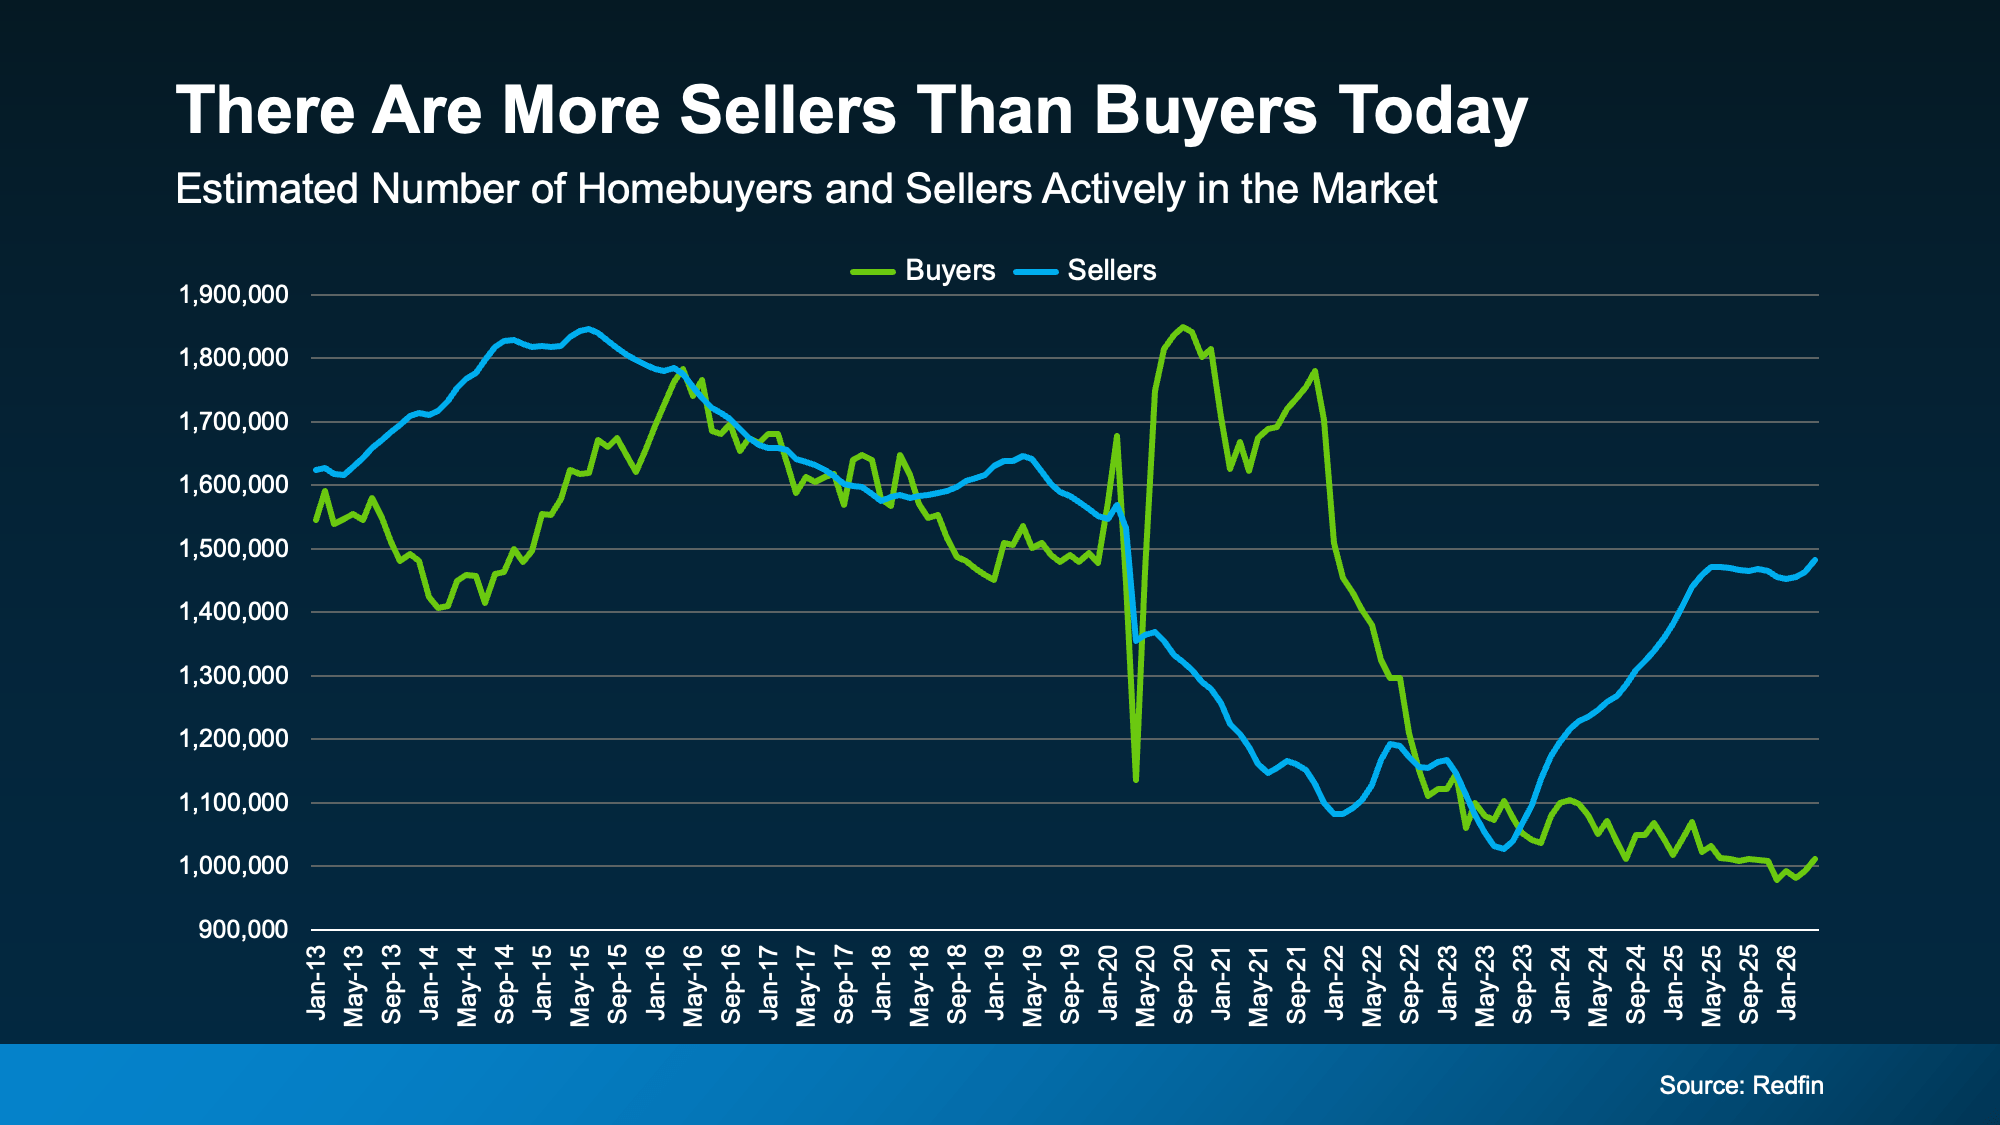
Redfin data shows there are more sellers than buyers active today. And that shifts the market dynamics (see graph below):

a graph of sales and buyers

That doesn’t mean every market favors buyers. Far from it. In some areas, homes are still selling quickly and sellers have plenty of leverage. But in others, buyers have more room to negotiate than they’ve had in years.


That’s why local market conditions matter so much when you make your decision.

For example, helping with closing costs may be worth considering if:

  • There are a lot of homes for sale in your area
  • Your house has been sitting on the market longer than expected
  • You’ve had showings, but no offers
  • You’re motivated to move quickly
  • Or you’re trying to keep a deal together during negotiations

After all, if it’s the thing that helps bring a serious buyer across the finish line, it could be well worth it.


Other Concessions You Could Offer Instead

Just remember, being flexible doesn’t mean saying “yes” to every request.  It means understanding which compromises actually help you accomplish your goals. Because there are always alternatives.

Redfin suggests considering other concessions if you’re not interested in helping with closing costs, like:

  • A home warranty
  • Repair credits
  • Flexible closing dates, or
  • Leave behind appliances or furniture

The right answer depends on what buyers in your market are asking for and what matters most to you. That’s exactly why working with an experienced local agent is so important.

Bottom Line

The sellers having the most success today are the ones who understand the market has changed and are adapting to meet it where it is.

Sometimes that means negotiating on closing costs. Sometimes it means offering something else. The key is knowing which concessions are worth it for our local market.

If you’re wondering what’s normal in our area, what’s worth negotiating, and where it makes sense to stand firm, let’s connect.

Buyer's Guide • June 12, 2026

What Rising Inflation Means for Your Move

Data shows inflation is moving in the wrong direction. But before the headlines send anyone into a panic, here’s what’s actually going on, why it matters for the housing market, and what it means if you’re thinking about buying or selling.

Inflation Went Up – Here’s What That Actually Means

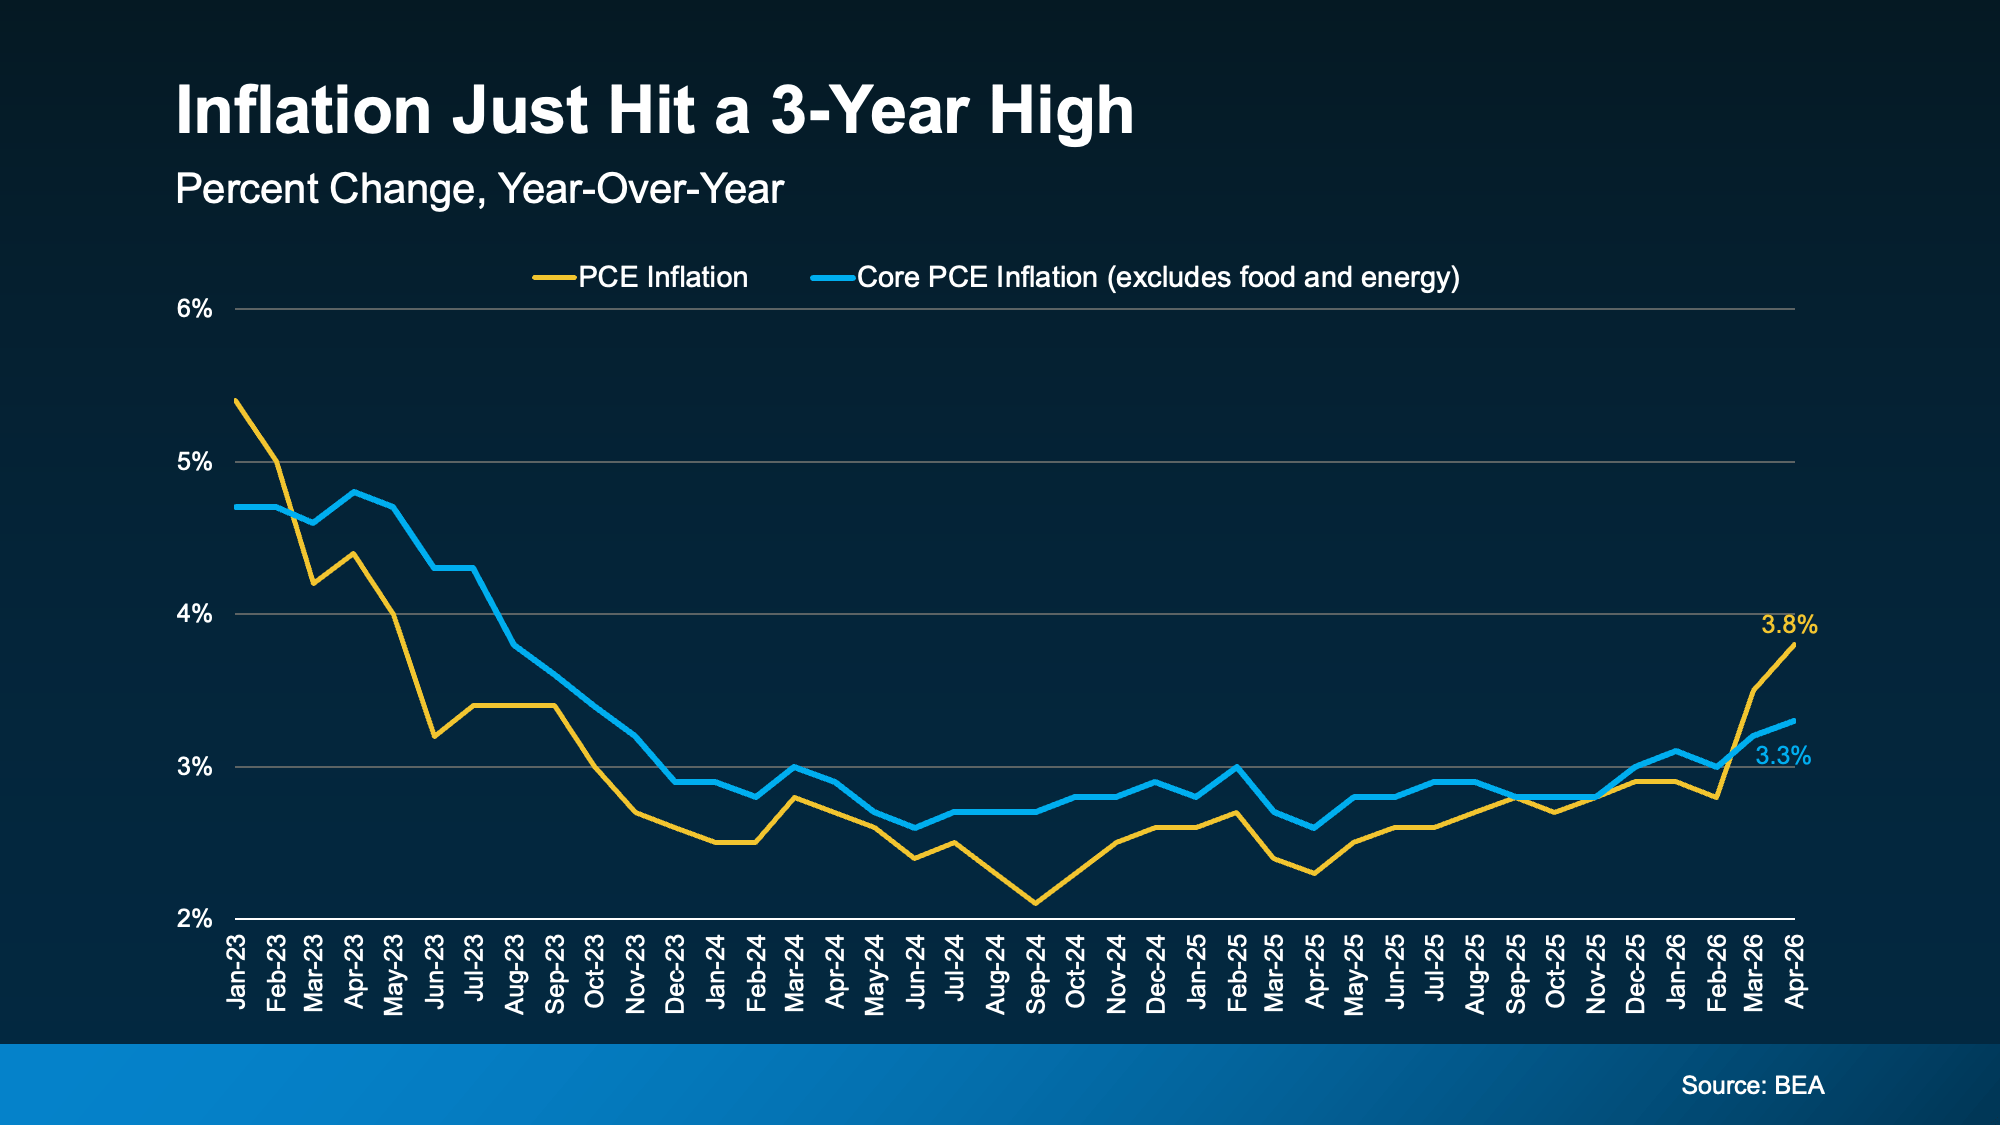
The government tracks inflation in a variety of ways. One is something called PCE – the Personal Consumption Expenditures Price Index. It measures how much more (or less) people are paying for goods and services compared to a year ago. And just based on your own expenses, you can probably guess which way that’s trending.

That’s the one everyone is talking about right now. Check out the yellow line to see how that’s spiked since February (see graph below). A big driver of this jump is the ongoing conflict in the Middle East, which has pushed gas and energy prices significantly higher.

a graph with blue and yellow lines

Now, you may have noticed there’s a second line. The blue line shows core PCE. That’s the same measure, but with gas and energy prices stripped out. The Federal Reserve (the Fed) actually watches this number most closely because energy prices swing around a lot and can be misleading.

And here’s the somewhat encouraging part.


Core PCE is rising, but not nearly as fast as the overall number.
That suggests a good chunk of the inflation spike we’re seeing right now is tied directly to what’s happening overseas. So, when that situation settles down, inflation may settle a bit, too.


Why This Matters for Mortgage Rates

Here’s the housing connection. When inflation is high, the Fed tends to keep the Federal Funds Rate elevated or even raise it to try to taper spending and cool inflation back down. And while it’s not a one-for-one relationship, that Federal Funds Rate can have an impact on your mortgage rate when you buy.

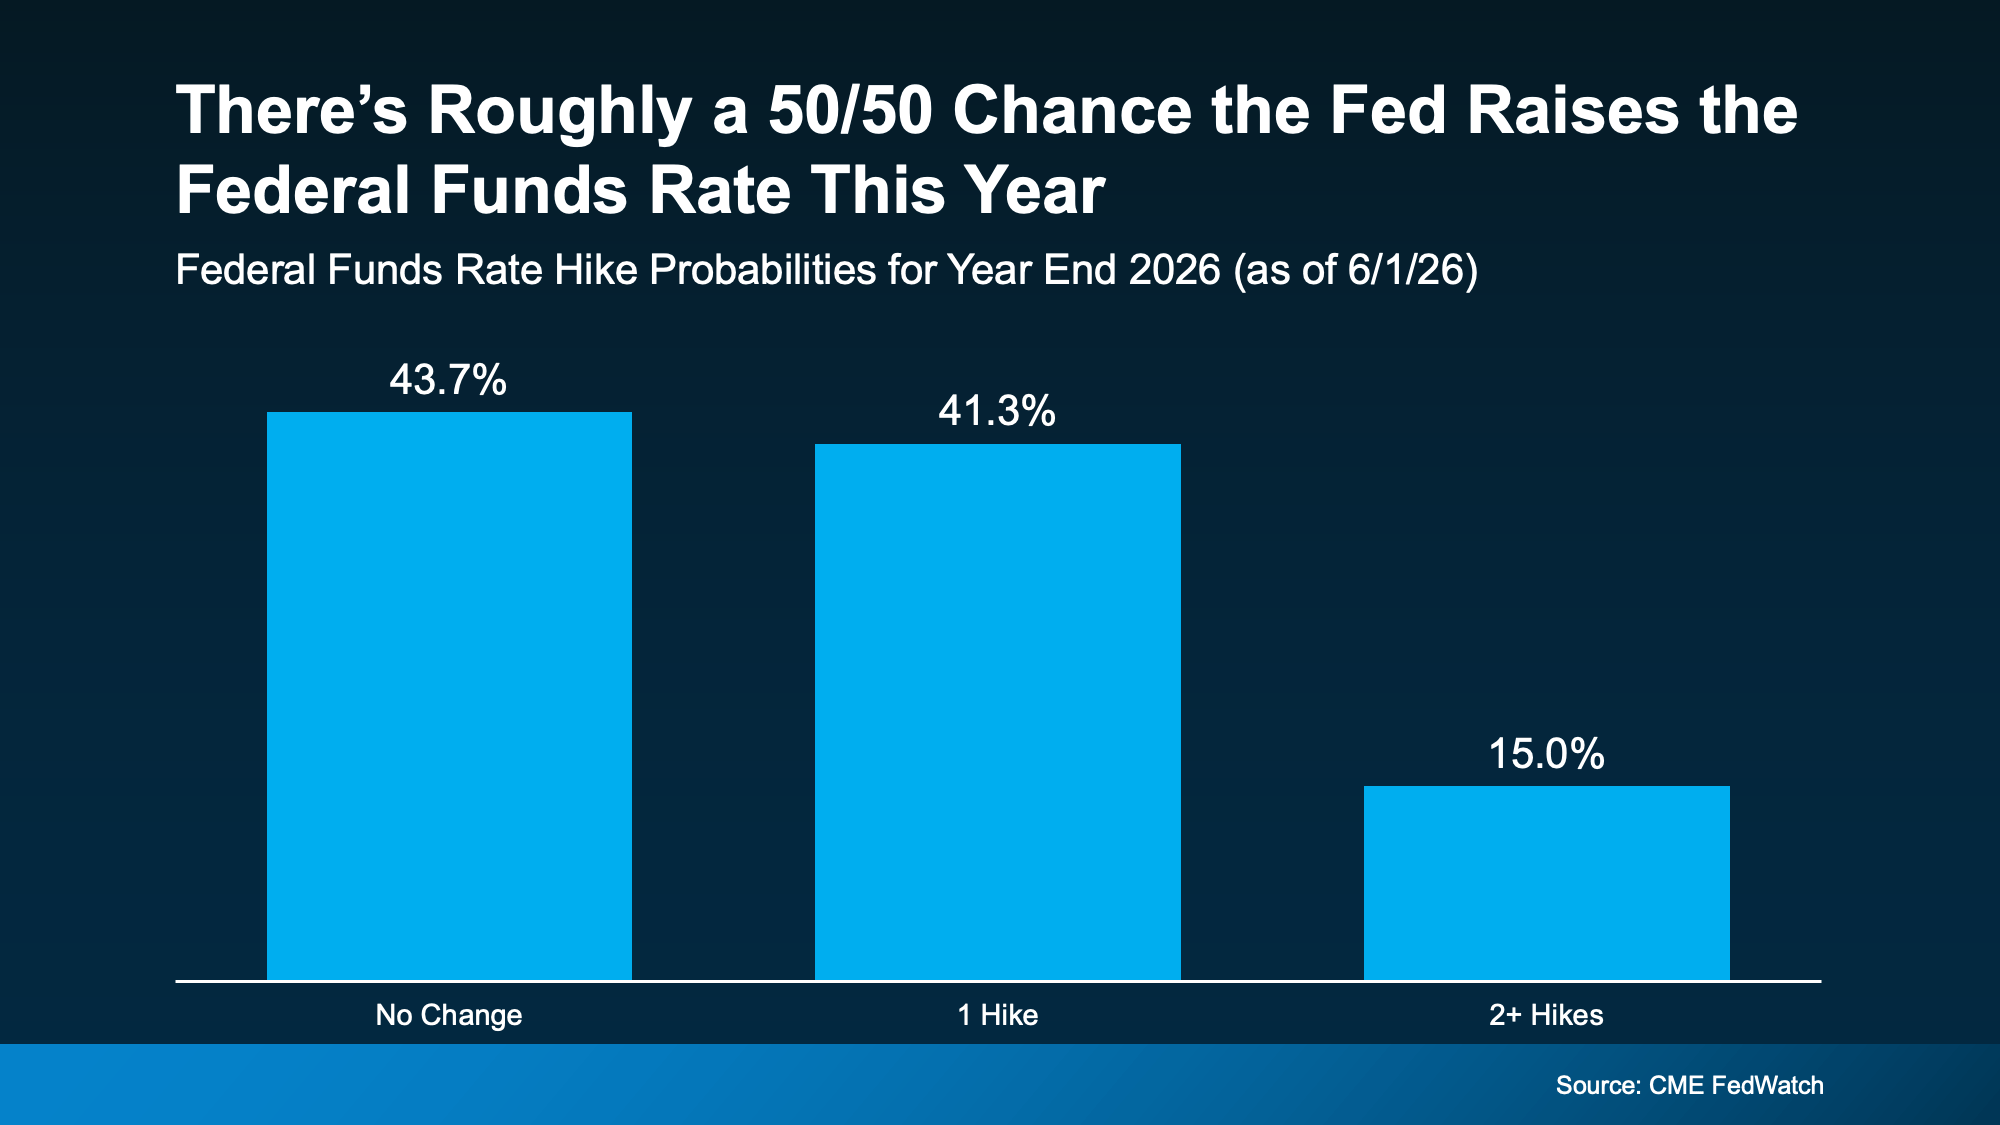
Right now, based on the information we have, there’s roughly a 50/50 chance the Fed actually raises the Federal Funds Rate before the end of 2026, according to CME FedWatch (see graph below):

a graph of blue squares

While it’s too soon to say where this goes for certain and if we’re headed for a rate hike, it does mean mortgage rates are probably not coming down as soon as most people were hoping.

If you’ve been waiting for rates to drop significantly before making a move, this report is a reminder that “higher for longer” is still very much on the table. It really all depends on where the economy goes from here. According to Bankrate:

“Oil prices and bond yields have dropped a bit . . . but they’re still way up compared to the start of spring. Until there’s a resolution to the war, look for both inflation and mortgage rates to stay high.”


But This Is Not 2008 – Not Even Close

Just remember, a tough economy does not equal a housing crash. The conditions today are very different from what led to the 2008 collapse. Here’s why:

  • Inventory is still relatively low. There’s no flood of homes hitting the market.
  • Most homeowners today have strong equity in their homes.
  • Lending standards are far stricter than they were before 2008.
  • Today’s challenge is affordability, not a wave of distressed underwater sellers.

Uncomfortable and unhealthy are not the same thing. The market feels hard right now, but “hard” and “crashing” are very different.


You Still Have Options. Here’s What To Do.

High rates don’t mean homeownership is out of reach. It just means the path looks a little different. There are real strategies that can help, depending on your situation:

  • Ask your lender about different loan options. Adjustable-rate mortgages (ARMs) or rate buydowns may help lower your monthly payment in the short term.
  • Explore first-time buyer programs, down payment assistance, or seller concessions that could help offset costs.
  • Stay in close touch with a trusted agent and lender. When rates shift, and they will, you’ll want to be ready to move fast.

The right strategy, tailored to your goals, matters a lot more than waiting for the perfect moment that may never come.

Bottom Line

Inflation is still above where the Fed wants it, and that means mortgage rates are likely to stay elevated for a while. But for people who need to move, strategy matters far more than trying to perfectly time the market.

Wondering what this means for your specific situation? Reach out today. Let’s cut through the noise together and make a plan that actually works for you.

Buyer's Guide • June 7, 2026

Less House, More Home: Why Smaller Homes Are Paying Off for Today’s Buyers

You started shopping with a specific mental image of your future home in your mind. Then the houses in your budget came in smaller than you pictured.

That’s the reality for a lot of buyers right now. Affordability is tight.

But don’t let that discourage you. Going smaller might actually be a smart play in today’s market – and the upside can be bigger than you’d think. Let’s break down two places to look where smaller won’t necessarily feel like a compromise.


Homebuilders Are Focused on Smaller Options Lately

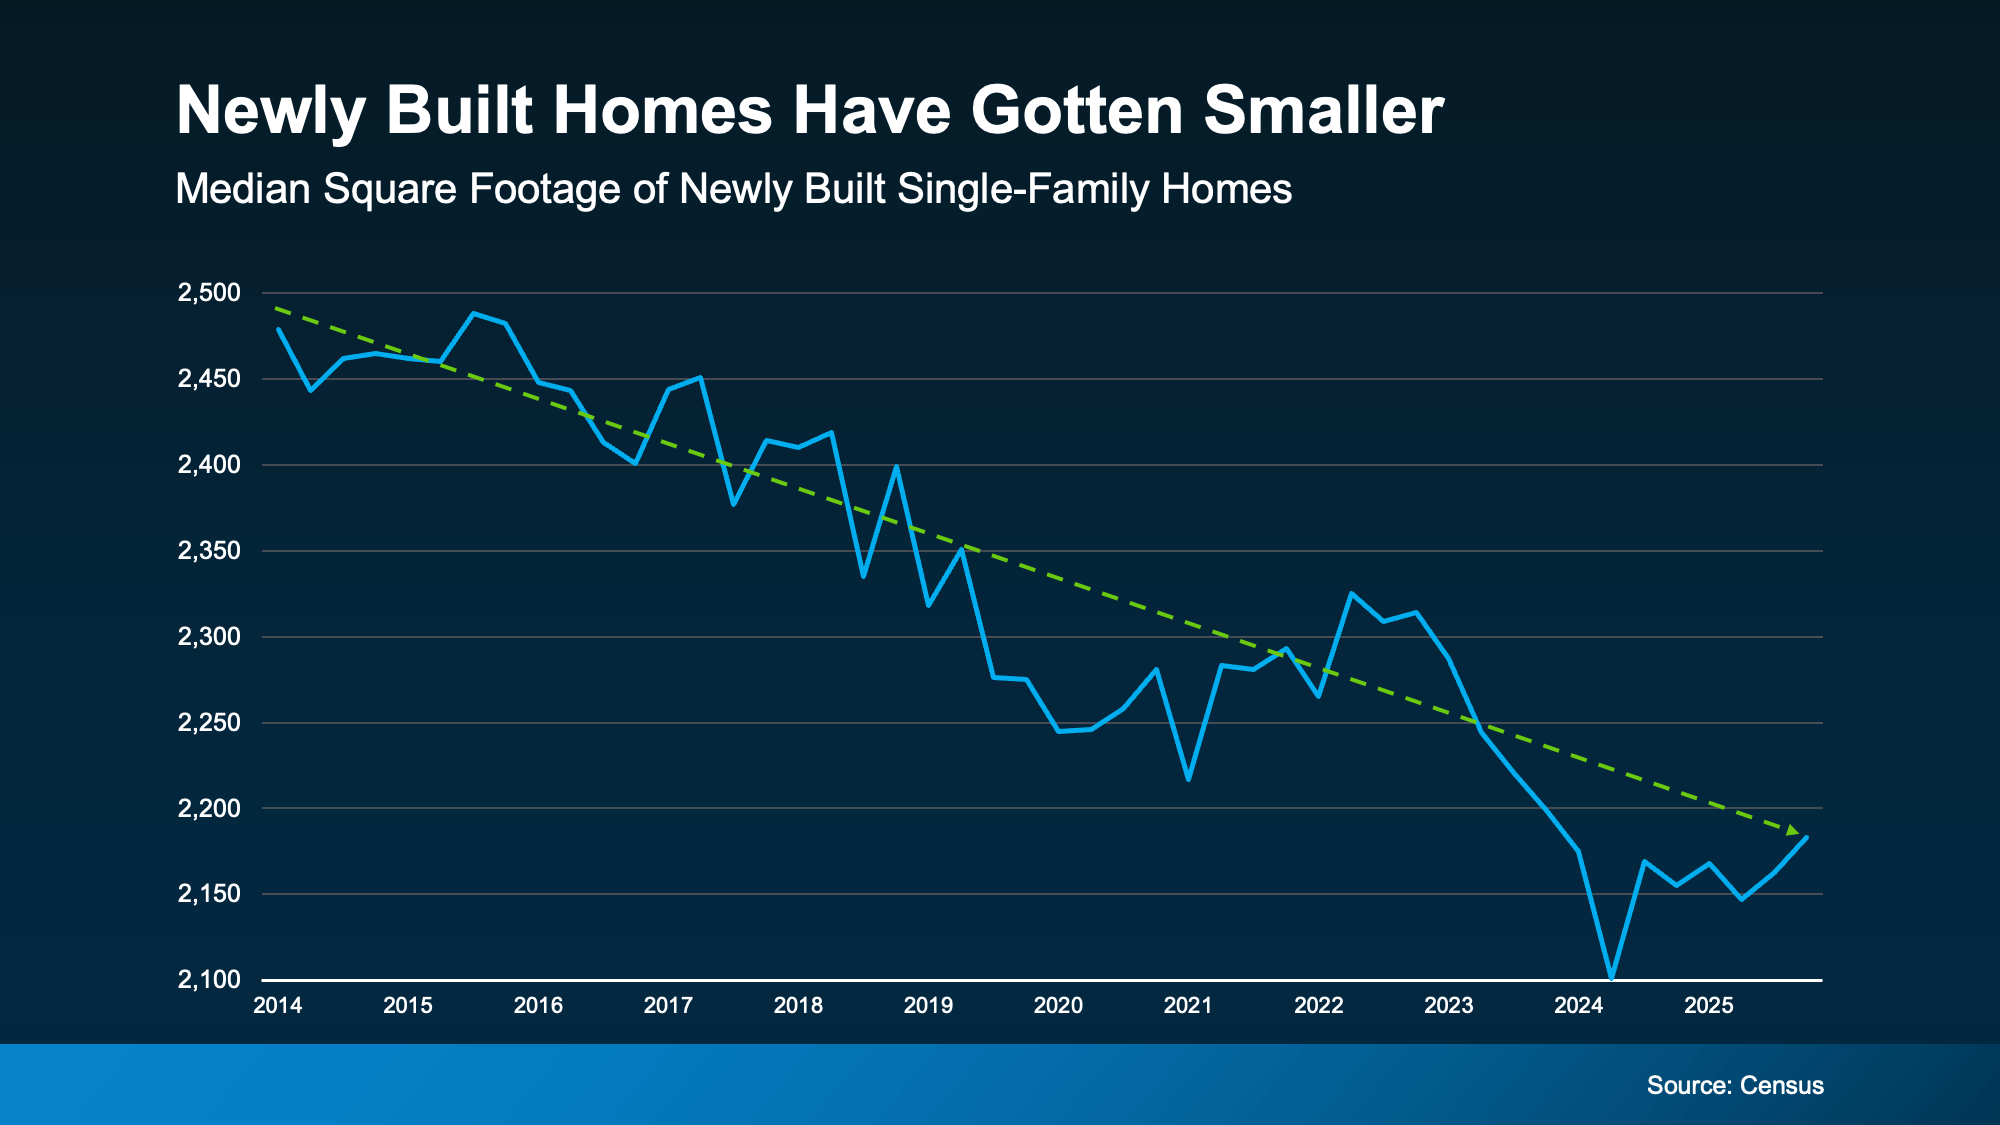
For starters, smaller is kind of on trend right now. Newly built homes have been shrinking for years. According to the latest data from the Census, the median square footage of new single-family homes has been falling overall since 2014 (see graph below):

a graph of a graph showing a line of a house

Why? Builders focus on the types of homes consumers want the most. After all, they want to build what will actually sell. And for the past decade, buyers seem to agree less is more.

Especially right now, when affordability is a key concern, they’re building homes with smaller square footage than a decade ago. And that’s good because that may be more within budget for many buyers. It’s part of why new home prices recently hit a 5-year low.


So, if you’re not getting excited about any of the existing options at your price point, it may be time to check out what builders are doing in your area.

You may find brand-new options you really love with all the latest and greatest features. And if you’ve got modern appliances and design, maybe slightly less square footage doesn’t feel like that much of a compromise anymore, especially if the house is move-in ready.


Condos Are Opening Up Another Path

Just in case you don’t have a ton of new builds in your area, another avenue worth exploring is condominiums or condos.

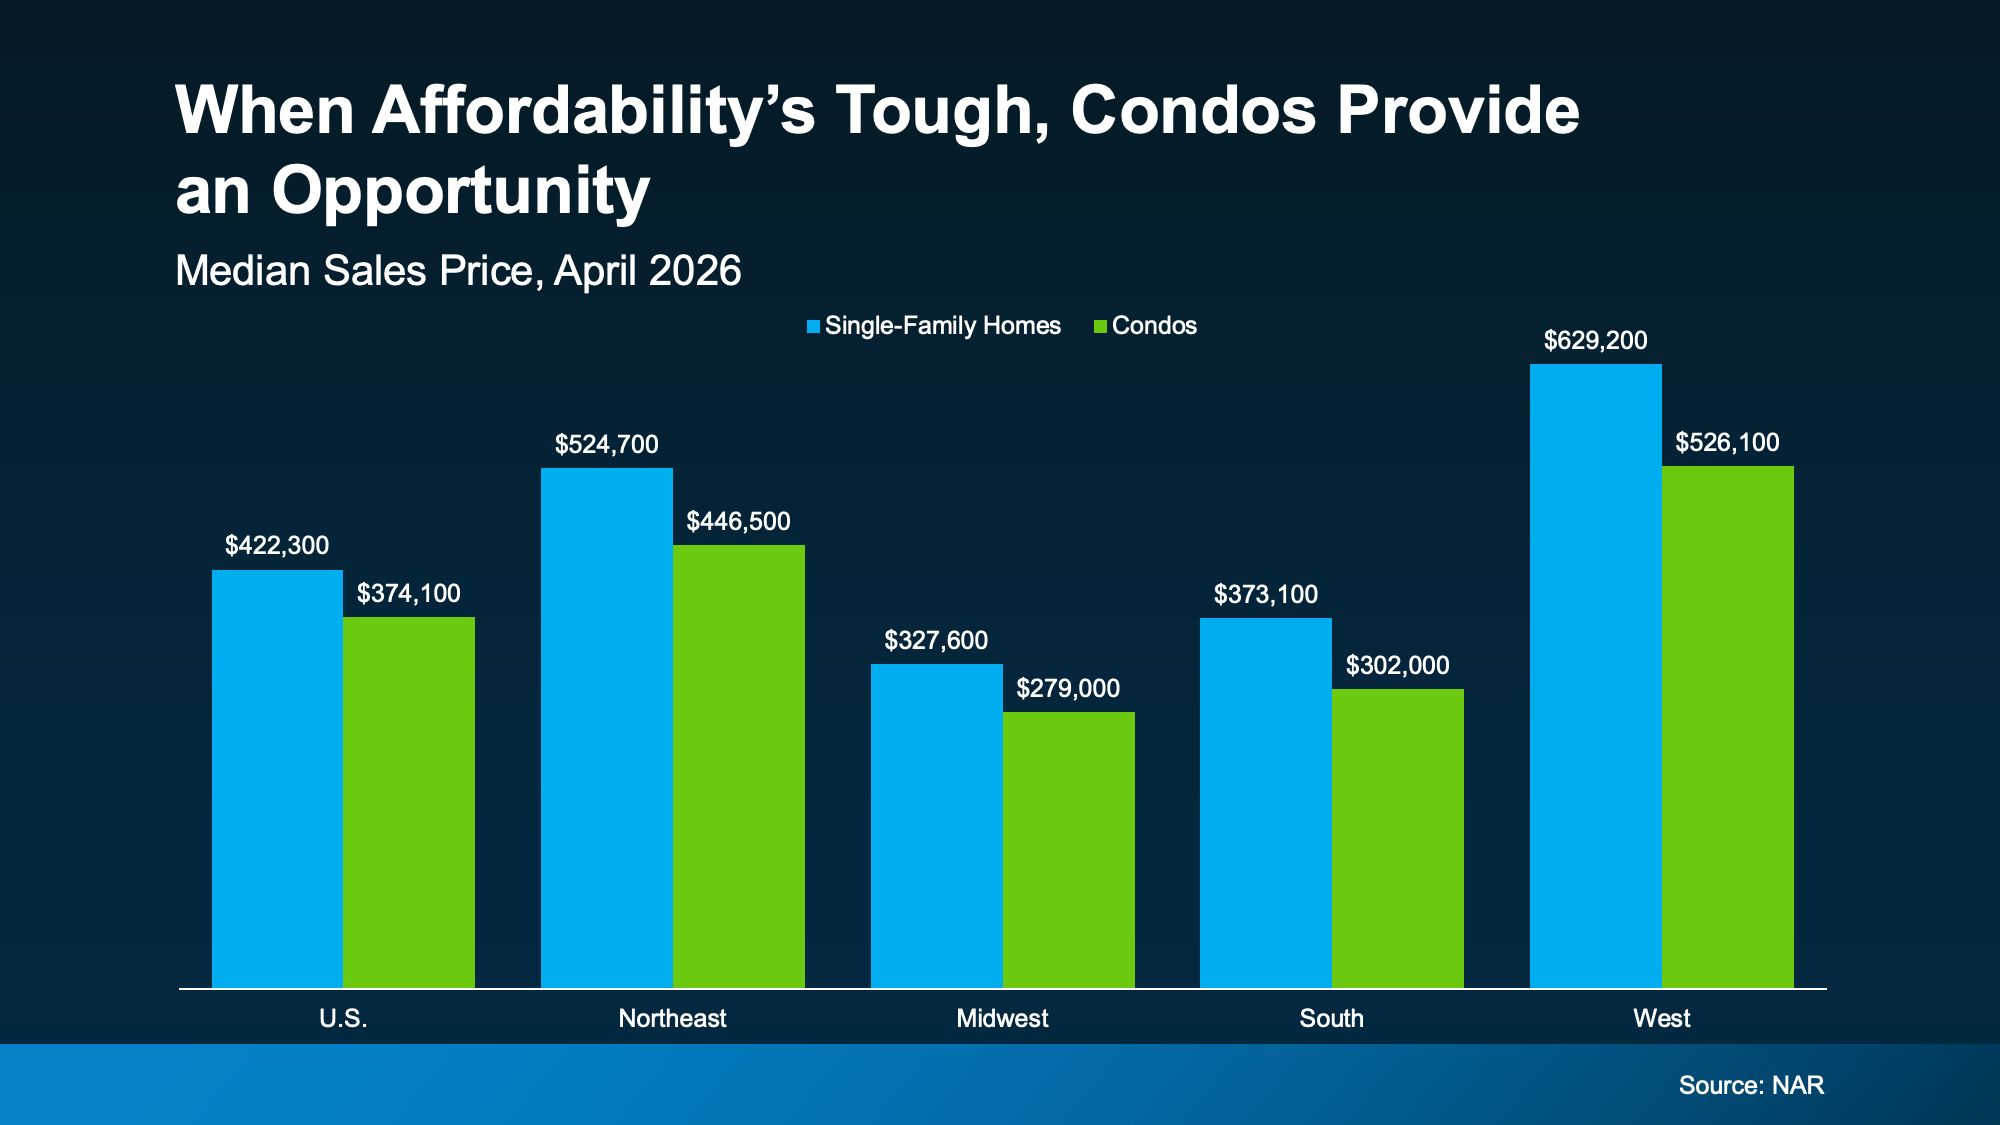
For buyers crunching numbers to make the math work, condos can take real pressure off the budget. According to the National Association of Realtors (NAR), the median price for condos is less than the median for single-family homes in every region (see graph below):

a graph of a number of blue and green bars

Part of that is because condos are typically smaller. And smaller square footage can come with a smaller price tag too. That’s a selling point to affordability-strapped buyers right now – and it’s one of the reasons we’re seeing a bump in condo sales.

The number of condos sold rose 2.7% from just a month ago. It’s also up year over year, according to NAR. Ali Wolf, Chief Economist for New Home Source, explains why more buyers are going this route:

“In addition to favoring smaller floor plans, more consumers are showing a willingness to live in an attached home. This shift is not driven by a preference for shared walls, but by a pursuit of value.”


The Community Does Some of the Heavy Lifting

Here’s why smaller may still work for you. Whether it’s a condo complex or a neighborhood of detached single-family homes, the right community can give you back in amenities what you trade in square footage.

Many developments are designed so the home is just one piece of where you actually spend your time. Master-planned communities often include walking trails, pools, fitness centers, co-working spaces, and outdoor gathering areas – the kind of features that pick up where your floor plan leaves off.

No room for a dedicated office? The co-working space might be just a five-minute walk away. Want a place to work out? It’s already built in with the shared gym. And features like that can make opting for a smaller footprint feel less like a compromise – and more like a big lifestyle upgrade.

Bottom Line

Today’s smaller single-family homes and condos have more going for them than the square footage suggests. They can give your budget some breathing room and put you in a community designed with lifestyle in mind.

Curious about the options in our area? Let’s connect.

Buyer's Guide • May 28, 2026

Newly Built Home Prices Hit a 5-Year Low

If you’ve always assumed a newly built home is just not in your budget, you should know the math just got a little friendlier.

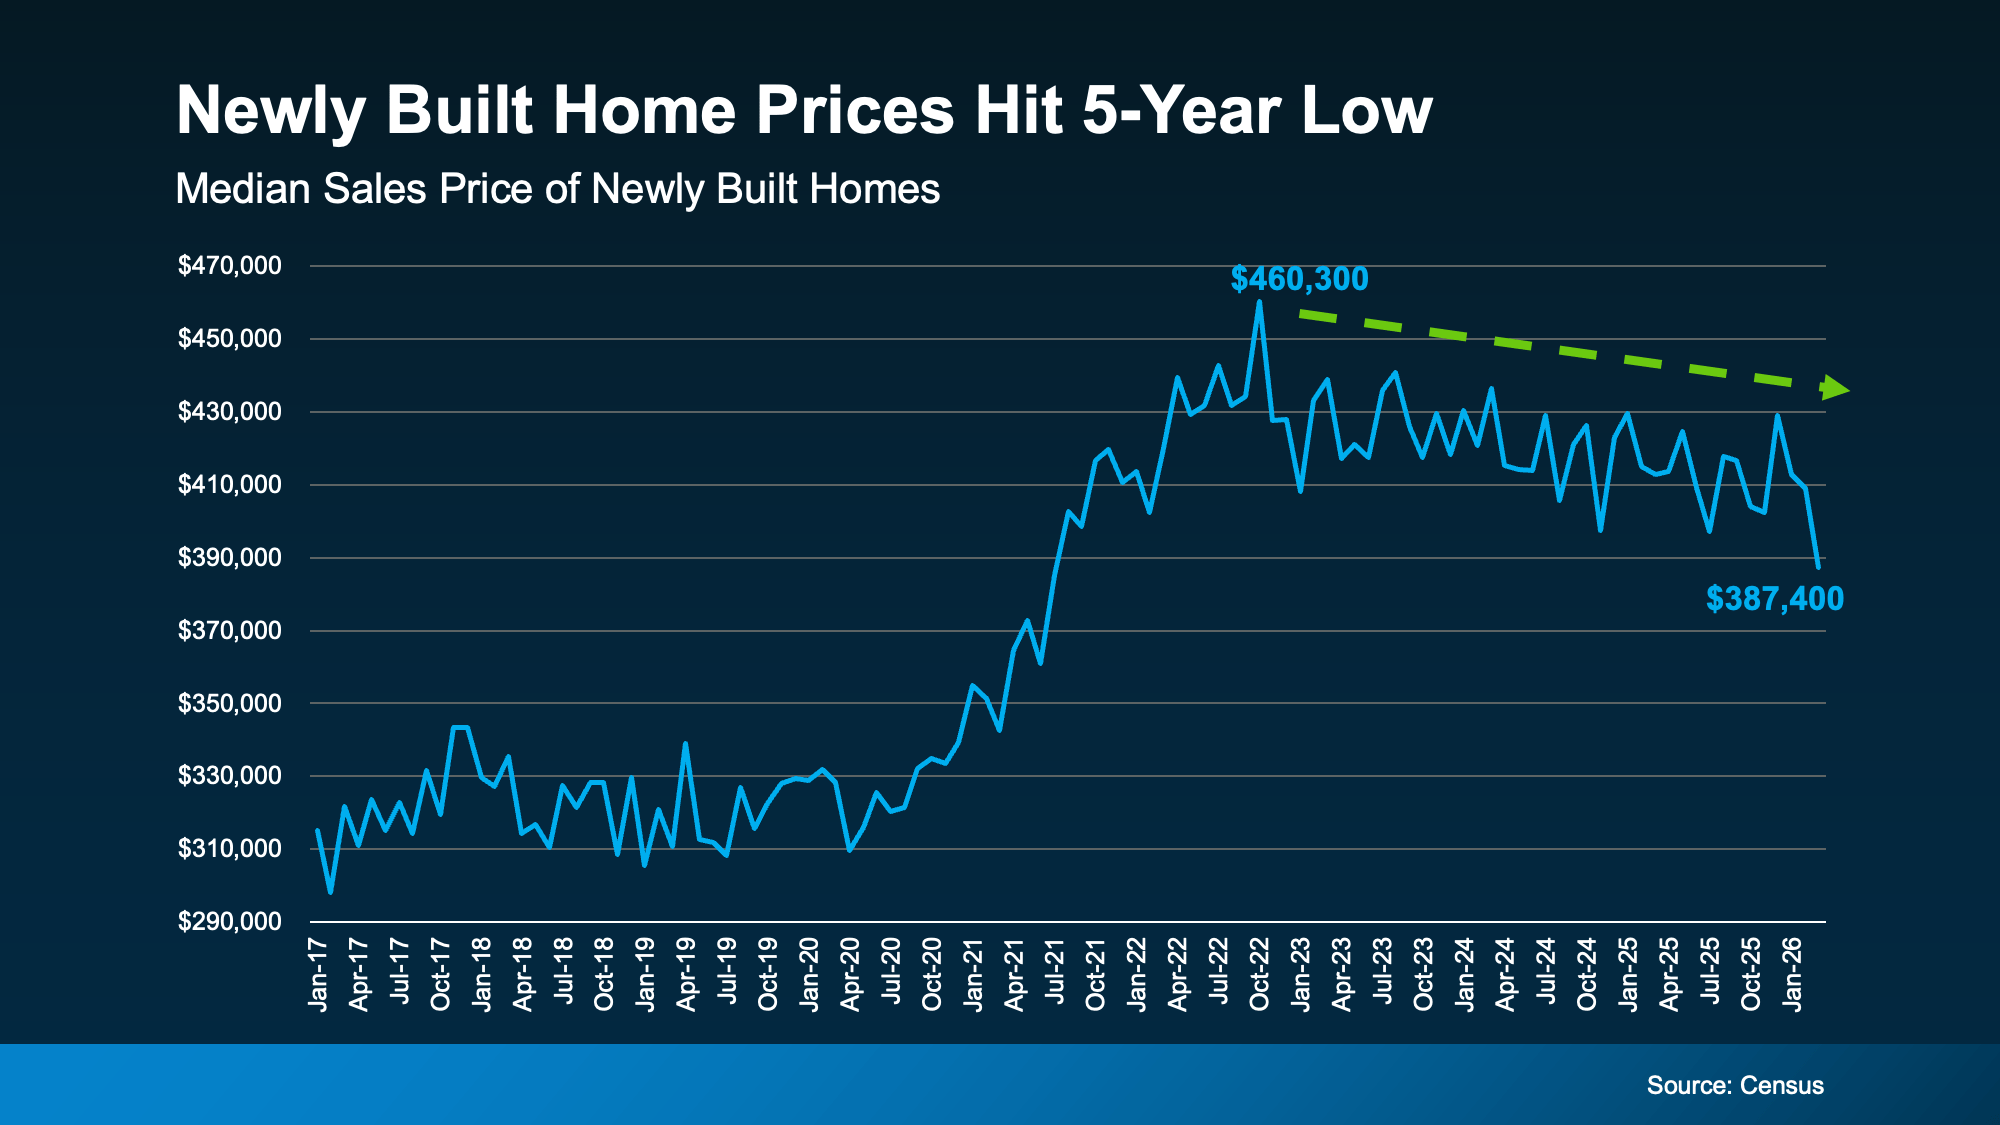
The median sale price of a newly built home is now at its lowest level since 2021, according to the latest data from the Census. And on top of that, builders are still rolling out incentives to bring buyers through the door.

Here’s what’s happening, and what it means if you’re shopping right now.


Prices on Newly Built Homes Have Come Down

After a steep climb during the pandemic years, prices have eased a bit. The median sale price of newly built homes is sitting at about $390,000. That’s the lowest it’s been in nearly five years (see graph below):

a graph of a home prices

While local markets vary, the national trend is moving in your favor, especially if you’re a first-time buyer. According to Zonda, prices in the entry-level price range have dropped roughly 2.7% over the past 12 months – more than any other price tier.

That doesn’t mean every home in every market is suddenly affordable. But it does mean that, broadly, you’ll see the best prices on new builds since 2021, if you’re buying now.


Why This Isn’t a Repeat of 2008

And just in case you’re thinking it, lower prices don’t mean the new home market is in trouble. Builders today are being intentional about how much inventory they have, so it doesn’t pile up the way it did in 2008.

If you look back up at the graph, you’ll see that even after the recent improvement in new home prices, they’re still higher than pre-pandemic norms. So, this isn’t a crash. It’s a builder strategy to keep inventory moving.


Homebuilders Are Still Sweetening the Deal

Lower sticker prices aren’t the only break buyers are getting. According to the National Association of Home Builders (NAHB), 60% of builders are currently offering some form of incentive to attract buyers. Those typically include:

  • Help with closing costs: Some builders are covering thousands of dollars in fees to reduce the upfront cost of buying.
  • Extra upgrades: Think premium finishes, appliance packages, and designer features, often added at no extra cost.
  • Mortgage rate buydowns: When the builder pays to lower your mortgage rate, which reduces your monthly payment.
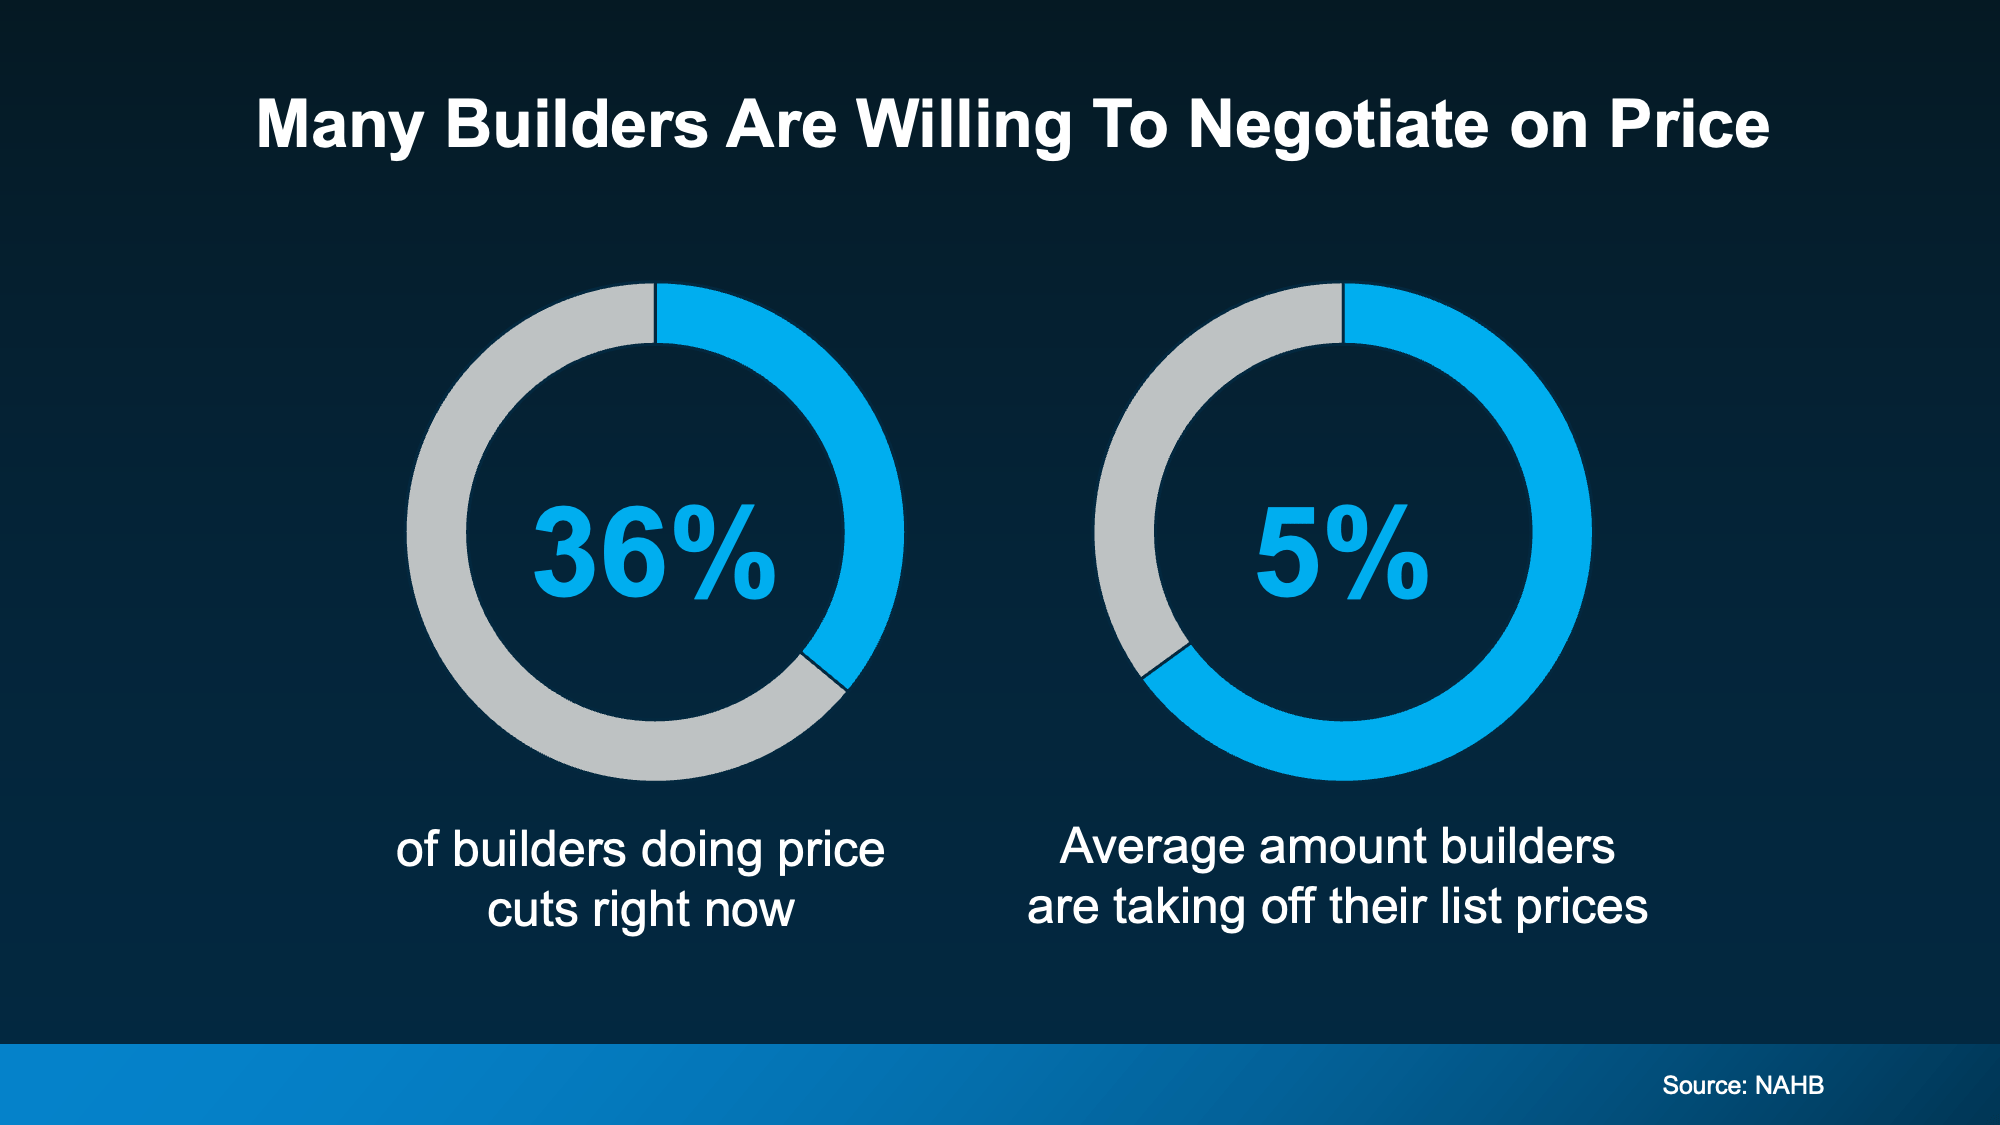
  • Price cuts: Over one in three builders (36%) are cutting prices right now, averaging about 5% off list price (see graph below):

a blue and grey pie chart

That last point catches a lot of buyers off guard – most assume that builders won’t budge on price.

But builders need to move what they’ve built. That’s a different mindset than a homeowner deciding whether to budge on price. So, you may find they’re more open to adjusting the price than you’d think. As Joel Berner, Senior Economist at Realtor.com, puts it:

“. . . many existing-home sellers resort to taking down their listing instead of taking less than their desired price, but builders are more motivated to sell their inventory than owner-occupants . . .”

And if you use the version of the graph that shows 2008 prices, you can even reference that in this explainer.

Bottom Line

Builder incentives and lower new home prices are working to your advantage in a way they haven’t in years. Want to see what’s available in your area and what kind of deal a builder may be willing to make? Let’s connect.

Buyer's Guide • May 15, 2026

Could Co-Buying Be the Answer for Some First-Time Buyers?

For a lot of would-be first-time buyers, affordability is the thing that’s standing in the way. But some buyers are getting creative and finding a way to still make the numbers work – and that’s through co-buying.


The Dream Is Still Alive. The Math Just Isn’t Working for Everyone.

Young people haven’t given up on the dream of owning a home – not even close. According to FirstHome IQ, homeownership still ranks among the top life goals for the next generation.

The problem? 73% of Gen Z and millennial buyers cite affordability as the reason for not making homeownership a priority. And it shows. First-time buyers now make up just 21% of all home purchases, the lowest share since the National Association of Realtors (NAR) started tracking the data in 1981.

But still, some buyers are making it happen. And a portion of them are turning to co-buying to get their foot in the door.


So, What’s Co-Buying?

Co-buying means purchasing a home with someone else, like a friend, sibling, or unmarried partner. You combine incomes, split the down payment, and share monthly costs. For some people, it’s a creative way to turn “someday” into a concrete move-in date that’s just around the corner.

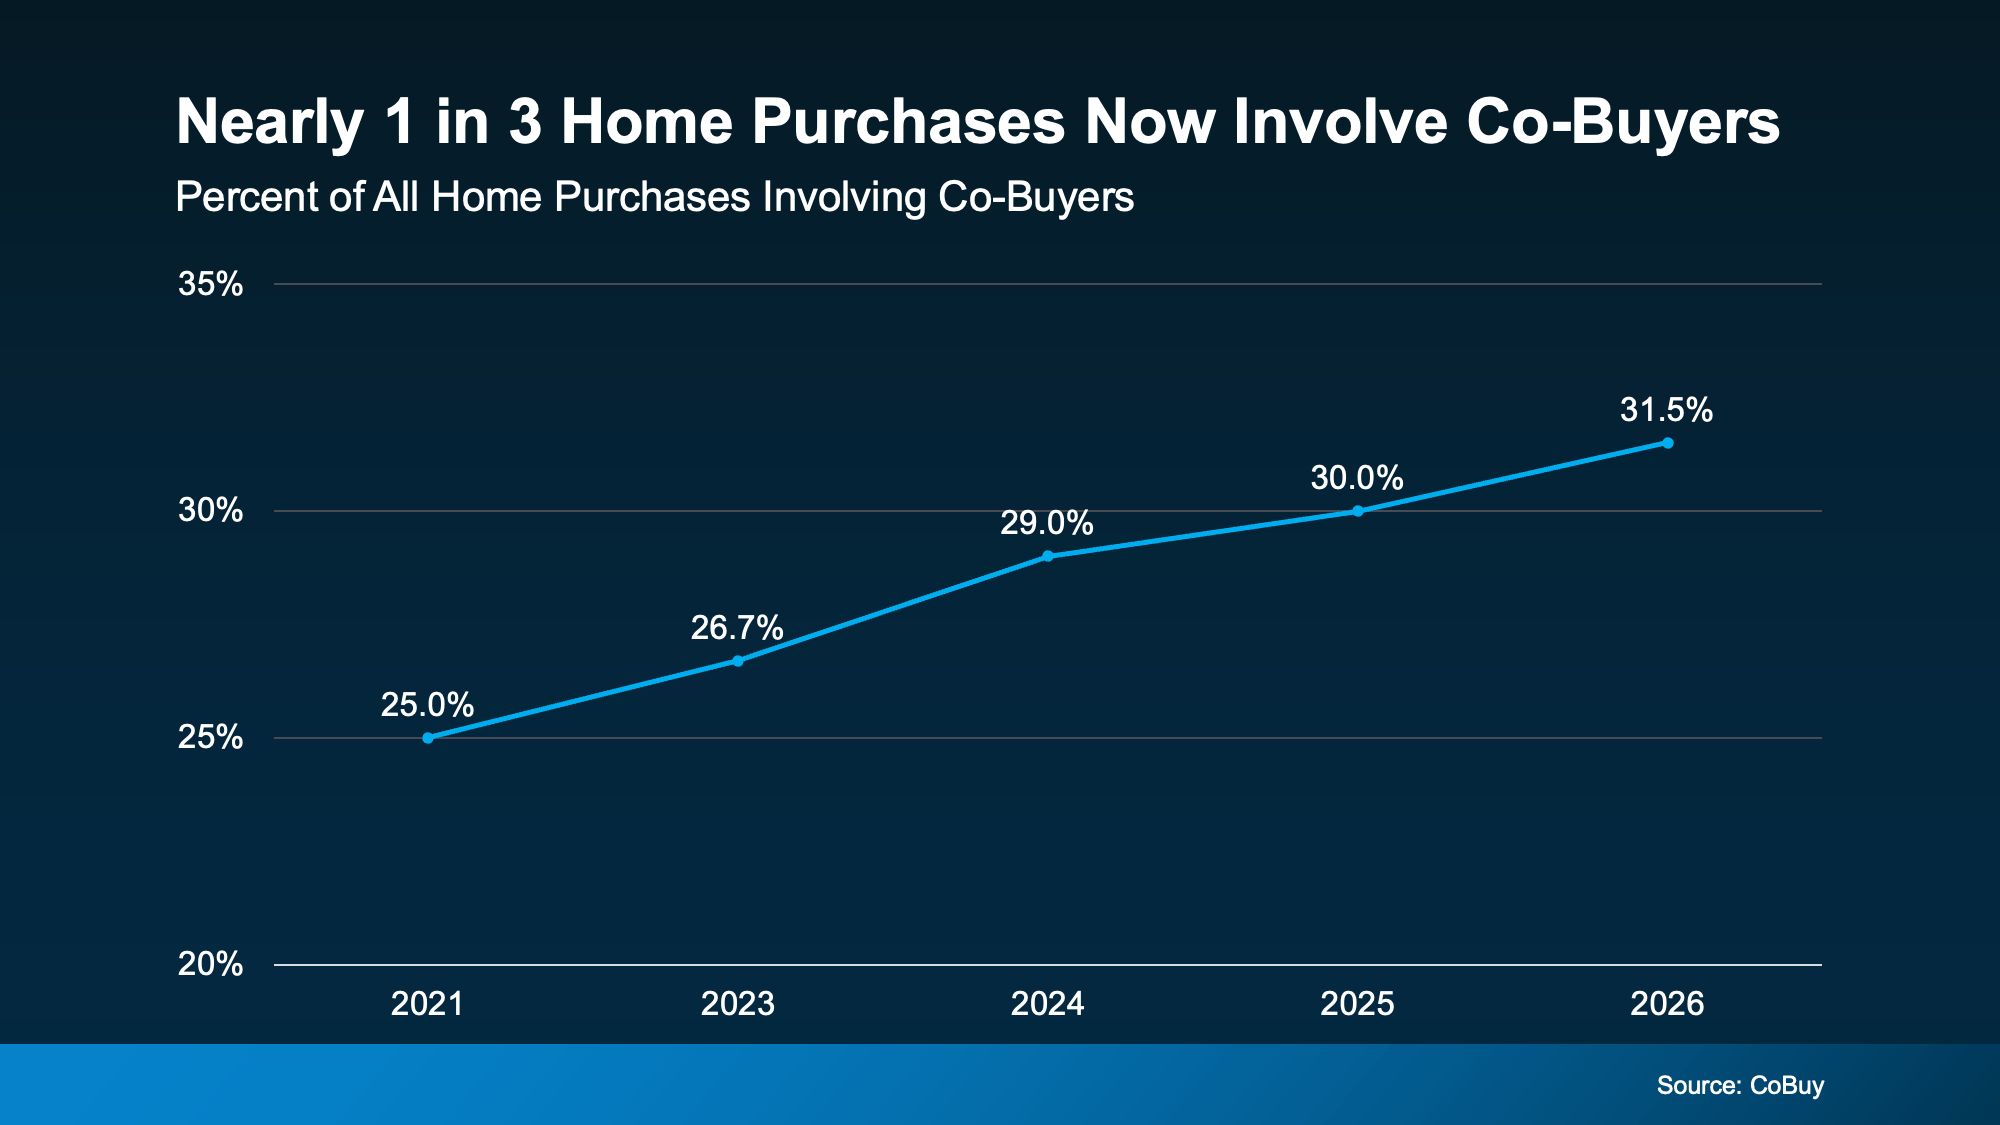
And it’s catching on fast, just look at where things stand today. According to CoBuy.io, 64 million Americans now co-own a home with someone they’re not married to. In fact, 31.5% of home purchases involve co-buyers (see graph below):

Why It Works

Here are just a few of the top reasons buyers are going this route, according to NerdWallet:

  • Quicker path to homeownership: If owning a home is a serious goal for you, buying with someone else can help make that reality on a shorter timeline. Two or more people can save up a down payment a lot faster than one. That’s less time waiting and more time building equity in a place that’s yours.
  • More purchasing power: With multiple incomes going toward the home purchase, you might be able to afford a nicer home or live in a more popular neighborhood. Sometimes teaming up means getting the home you actually want, not just the one you can barely afford on your own.
  • Easier loan qualification: Added income from more than one buyer can also help with your debt-to-income (DTI) ratio, which the lender will calculate based on all the borrowers.
  • Lower housing costs: Splitting up a mortgage payment multiple ways could maybe even make owning less expensive than renting. Plus, sharing costs can make repairs or renovations more manageable, too.


Things To Keep in Mind

If you’re considering going this route, there are some things you’ll want to think over. For starters, co-buying works best with people you trust and share financial goals with. So, before moving forward, make sure everyone agrees on how costs are split, who handles what, and what happens if one person wants to sell down the road.

That’s why a written co-ownership agreement can be a smart move. It keeps everyone on the same page and helps avoid headaches down the line. Think of it less like a legal formality and more like a game plan for your new investment.

Bottom Line

Affordability challenges are real, but they don’t have to mean waiting indefinitely. Co-buying is helping some first-time buyers stop waiting and start putting down roots.

If you’re curious whether it could work for your situation, let’s talk. Reach out today and let’s figure out your path to homeownership together.